


Phenol Market Forecast Reveals Promising Opportunities Across Resins, Adhesives, Plastics, Laminates, and Specialty Chemical Applications
The global phenol industry is experiencing measured growth as phenol continues to serve as an important chemical intermediate for plastics, resins, pharmaceuticals, coatings, adhesives, and specialty materials. Its broad industrial utility allows demand to remain connected with multiple sectors, including automotive, construction, electronics, chemicals, and healthcare.
The Phenol Market is projected to increase from USD 17.24 billion in 2025 to USD 24.125 billion by 2035, representing a CAGR of 3.42% during 2026–2035. Growth is supported by increasing consumption of downstream derivatives and investments in integrated chemical manufacturing.
Bisphenol-A remains a major product segment, accounting for 41.2% of market share in 2025. Its importance is closely linked with polycarbonate and epoxy resin production. These materials are widely used in electronics, automotive components, wind-energy applications, construction products, and industrial equipment where strength, durability, and thermal stability are required.
Phenolic resins provide another important source of demand. They are used in wood-panel bonding, friction materials, foundry binders, insulation, and molded products. Their resistance to heat and chemicals makes them valuable in demanding industrial environments.
Automotive applications are particularly significant, representing 19.7% of revenue share in 2025. Phenolic compounds are increasingly used in under-hood components, brake systems, composites, and thermal barriers. The transition toward electric vehicles is also creating new opportunities for phenolic materials in battery-related applications.
Technological modernization is influencing production as well. Producers are improving catalyst systems, process control, water recycling, and energy efficiency. At the same time, bio-based and lignin-derived routes are attracting interest as manufacturers look for lower-carbon alternatives.
Asia-Pacific remains the dominant regional market, accounting for 50.2% of market share in 2025. China, South Korea, Japan, India, and other Asian economies benefit from integrated petrochemical and downstream manufacturing capabilities.
Overall, the industry is expected to expand steadily through 2035 as demand from electronics, automotive, construction, pharmaceuticals, and chemical manufacturing offsets challenges such as feedstock volatility and substitution pressures.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
According to Future Market Insights (FMI), the global Dredging Market is entering a period of steady expansion as governments, port authorities, and marine infrastructure operators increase investments in waterway maintenance, port development, coastal protection, and shoreline resilience. the market is projected to grow from USD 17.3 billion in 2026 to USD 21.3 billion...

Decorative laminates are engineered surface materials designed to enhance the appearance, durability, and functionality of furniture and interior surfaces. They are manufactured by bonding multiple layers of kraft paper, decorative paper, and resin under high or low pressure to create a strong, long-lasting finish. Widely used for furniture, wall panels, countertops, flooring, cabinets, and...

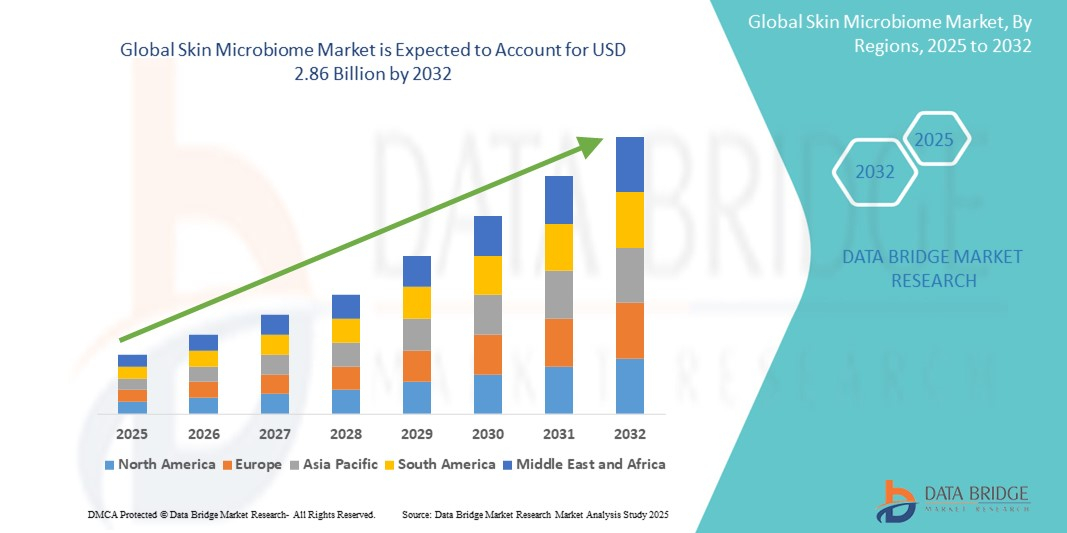
According to the latest report published by Data Bridge Market Research, the Skin Microbiome Market The global skin microbiome market was valued at USD 1.03 billion in 2024 and is expected to reach USD 2.86 billion by 2032. During the forecast period of 2025 to 2032 the market is likely to grow at a CAGR of 13.68%. Market definition mentioned in this Skin Microbiome...
Advanced Driver Assistance Systems (ADAS) are intelligent vehicle safety technologies designed to support drivers, improve road safety, and minimize the risk of accidents. These systems combine advanced technologies such as cameras, radar, lidar, sensors, and artificial intelligence (AI)-driven software to continuously monitor the vehicle’s environment, analyze potential hazards, and...
The China antibodies market is on a trajectory of impressive growth, fueled by a projected market size of $94.0 billion by 2035, representing a staggering compound annual growth rate (CAGR) of 13.72%. This remarkable surge is indicative of the increasing demand for advanced therapeutic options and the rise of personalized medicine. The anticipated market volume of $22.84 billion in 2024 and...
