Metallurgical Additive Market Insights Reshaping Demand
The Metallurgical Additive Market focuses on materials introduced during metal processing to enhance properties and enable advanced manufacturing. Types include fluxes, alloying agents, metal powders, and coatings. Applications span steel manufacturing, foundry, metalworking, additive manufacturing, and surface treatment.
Market Size & Forecast
The market was valued at $2.79 Billion in 2024. Projections indicate growth to $2.98 Billion in 2025. A CAGR of 7.08% is forecast for 2025-2035, reaching $5.92 Billion by 2035.
Market Trends & Insights
Investment activity targets advanced alloy development. Companies allocate resources toward rare earth element alternatives and high-performance material formulations.
Adoption patterns show increasing integration of additive manufacturing. Metal powders designed for 3D printing experience elevated demand.
Demand trends indicate growing requirements for lightweight materials. Fuel efficiency standards and emission regulations drive material innovation.
Market Drivers
Expansion of end-use industries provides growth momentum. Automotive, aerospace, and construction development increases additive demand.
Rising demand for lightweight materials creates new opportunities. Aluminum, titanium, and specialty alloy additives benefit.
Advancements in 3D printing technologies reshape production. Metal additive manufacturing continues to mature.
Market Challenges
Raw material cost fluctuations challenge profitability. Metal prices and rare earth availability are volatile.
Supply chain complexity increases with global operations. Managing sourcing, production, and distribution requires coordination.
Regulatory barriers vary across jurisdictions. Compliance requirements add cost and complexity.
Segment Analysis
Steel manufacturing and foundry represent largest segments. Metalworking and additive manufacturing follow.
Fluxes dominate by type. Metal powders gain share due to additive manufacturing expansion.
Automotive leads end-use demand. Aerospace and construction follow. Ferrous alloys dominate by material type.
Regional Insights
Asia Pacific maintains leadership through steel production and manufacturing. North America emphasizes additive manufacturing adoption.
Europe maintains significant share through advanced capabilities. Sustainability focus drives innovation.
Competitive Landscape
Höganäs AB, Sandvik AB, 3D Systems Corporation, Stratasys Ltd., EOS GmbH, and GE Additive lead the market.
Competition focuses on material innovation and application expertise. Sustainability and technical service differentiate.
Expansion includes capacity additions and technology partnerships. Acquisitions target niche capabilities.
Future Outlook
The industry evolves toward additive manufacturing integration. Investment opportunities exist in metal powder development.
Structural transformation favors manufacturers with material science capabilities. Future demand indicates strong growth with value migration toward higher-performance products.
Related Reports
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
Wenn ein Angebot heute noch Aufmerksamkeit holen will, reicht eine klassische Auswahl allein nicht mehr. Entscheidend ist eher, wo sich Nutzerverhalten und Spieldesign ineinander greifen, manchmal ziemlich unspektakulär, aber wirksam. Genau deshalb lohnt ein Blick auf Rabona Casino, weil sich an den aktuellen Spieletrends gut erkennen lässt, warum manche Plattformen einfach runder...
The global healthcare landscape is currently navigating a pivotal era in oncology, where the demand for effective cancer management has never been higher. Despite the emergence of targeted therapies and immunotherapies, chemotherapy remains a cornerstone of cancer treatment protocols worldwide. It is utilized as a primary treatment, a neoadjuvant therapy to shrink tumors before surgery, or a...
The global packaging industry is witnessing a significant transformation, driven by the increasing demand for product safety, extended shelf life, and consumer convenience. Among various packaging modalities, blister packaging has emerged as a cornerstone, particularly within the pharmaceutical and consumer goods sectors. This packaging method involves the use of pre formed plastic or foil...

The Crop Sprayer Industry is undergoing a significant transformation driven by technological innovation and changing agricultural practices. As farmers demand more efficient and sustainable solutions, the market is witnessing a shift toward advanced spraying technologies. Currently valued at approximately USD 6.19 billion in 2025, the industry is projected to expand further with a compound...
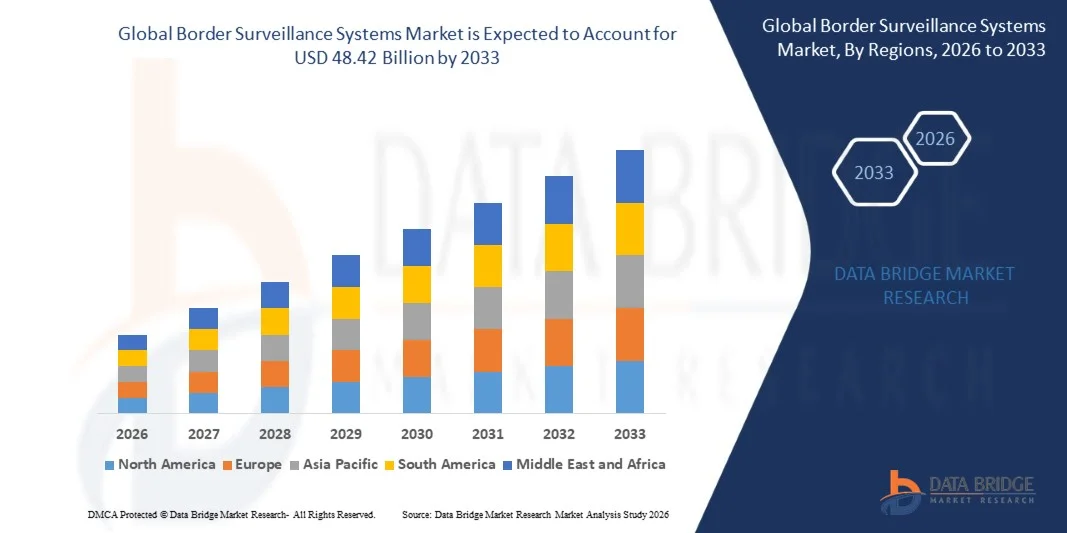
According to the latest report published by Data Bridge Market Research, the Border Surveillance Systems Market CAGR Value As per Data Bridge Market Research analysis, the border surveillance systems market was valued at USD 25.40 billion in 2025 and is projected to reach USD 48.42 billion by 2033, growing at a CAGR of 8.4% from 2026 to 2033. Border Surveillance Systems...