Semiconductor Dicing Lubricants Market Size, Share, Trends and Forecast to 2035
Market Overview
According to WiseGuy Reports, the Semiconductor Dicing Lubricants Market was valued at USD 800 million in 2024 and remained at USD 800 million in 2025. The market is projected to reach USD 1.5 billion by 2035, registering a CAGR of 5.9% from 2026 to 2035. Growing semiconductor demand, technological advancements, increasing automation, environmental regulations, and demand for cost-effective alternatives are supporting market development. Major companies profiled include ShinEtsu Chemical, Henkel, Precision Coating, Dow Chemical, Wacker Chemie, DuPont, Momentive Performance Materials, Universal Photonics, Asahi Glass, KMG Chemicals, Daubert Cromwell, Eastman Chemical, Trelleborg, Fujikura Kasei, BASF, and 3M.
Semiconductor dicing lubricants play an important role in semiconductor manufacturing processes by supporting cutting and dicing operations. As semiconductor devices become increasingly important across electronics, automotive, telecommunications, aerospace, and healthcare applications, manufacturers require materials that can support precision processing and consistent production performance.
Market Size Reached in 2025
The Semiconductor Dicing Lubricants Market was valued at USD 800 million in 2025, unchanged from USD 800 million in 2024. The market is closely connected to semiconductor production volumes and the continued expansion of advanced electronic devices.
Water-soluble, oil-based, and synthetic lubricants represent the major product types. Water-soluble formulations can support applications where easy processing and cleanup are important, while oil-based and synthetic alternatives address different performance and processing requirements.
Wafer dicing, chip dicing, and blade dicing are key application areas. As semiconductor manufacturing processes demand greater precision, lubricants are increasingly evaluated based on their ability to support efficient dicing operations and maintain processing quality.
Key Growth Drivers
Growing semiconductor demand is a primary factor supporting market expansion. The increasing use of semiconductors in consumer electronics, automotive systems, telecommunications equipment, healthcare devices, and aerospace technologies is supporting continued manufacturing activity.
The expansion of semiconductor production capacity is creating additional opportunities. New and upgraded manufacturing facilities require specialized materials and consumables to support increasingly sophisticated production processes.
Technological advancements are also influencing lubricant development. Semiconductor manufacturers require materials capable of supporting precision operations as device designs become more complex and manufacturing tolerances become increasingly demanding.
Increasing automation across semiconductor production is another growth driver. Automated manufacturing environments require consistent material performance and reliable process inputs, creating demand for lubricants designed to meet the requirements of high-throughput production systems.
Emerging Market Trends
The development of high-performance lubricant formulations is an important market trend. Manufacturers are focusing on materials that can support precision dicing while addressing processing efficiency and equipment requirements.
Environmental regulations are also influencing product development. There is increasing interest in eco-friendly lubricant alternatives and formulations that can help manufacturers address environmental considerations without compromising operational requirements.
Emulsion and non-emulsion formulations provide different options for semiconductor processing applications. Concentrated formulations can also provide flexibility in handling and preparation, depending on manufacturing requirements.
The growing automotive electronics sector is creating another important opportunity. Modern vehicles increasingly incorporate electronic control systems, sensors, communication technologies, and other semiconductor-based components, supporting demand throughout the semiconductor supply chain.
Expected Market Size by 2035
The Semiconductor Dicing Lubricants Market is projected to reach USD 1.5 billion by 2035. Growing semiconductor production capacity, demand for advanced technologies, increasing adoption of high-performance materials, automotive electronics expansion, and interest in environmentally conscious alternatives are expected to support this growth.
Consumer electronics and telecommunications will remain important end-use industries, while automotive applications are expected to provide additional opportunities. Aerospace and healthcare also require semiconductor components for specialized systems, creating demand across diverse manufacturing applications.
The expansion of semiconductor manufacturing in different regions can further support lubricant demand. As producers increase capacity and adopt more advanced processing technologies, specialized materials will remain important for maintaining efficient dicing operations.
Market CAGR
The market is forecast to expand at a CAGR of 5.9% from 2026 to 2035. This growth reflects the continued expansion of semiconductor applications and the increasing need for specialized materials in precision manufacturing processes.
Product development is expected to focus on performance, compatibility, processing efficiency, and environmental considerations. Suppliers that can provide formulations suited to evolving semiconductor manufacturing requirements may find opportunities as production technologies advance.
Competitive Landscape
The competitive landscape includes chemical manufacturers, specialty material suppliers, and companies providing formulations for semiconductor processing applications. ShinEtsu Chemical, Henkel, Precision Coating, Dow Chemical, Wacker Chemie, DuPont, Momentive Performance Materials, Universal Photonics, Asahi Glass, KMG Chemicals, Daubert Cromwell, Eastman Chemical, Trelleborg, Fujikura Kasei, BASF, and 3M are among the key companies profiled.
Competition is influenced by formulation performance, product consistency, technological capabilities, environmental characteristics, cost efficiency, and the ability to support semiconductor manufacturers across different production environments.
As semiconductor production expands across consumer electronics, automotive, telecommunications, aerospace, and healthcare applications, demand for specialized dicing materials is expected to increase. Advancements in semiconductor manufacturing, automation, high-performance formulations, and eco-friendly alternatives are likely to shape the market through 2035.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
The Vocal Fold Augmentation Market is growing as awareness of voice disorders and minimally invasive treatment options increases. WiseGuyReports estimates the market at USD 2.1 billion in 2025 and projects it to reach USD 3.5 billion by 2035, expanding at a 5.4% CAGR. Advances in biomaterials are improving the range of options available for vocal fold treatment. Injectable materials, autologous...

Hetero - one of the world's leading producers of Active Pharmaceutical Ingredients (APIs) and generic formulations - is expanding its team. About Hetero:Hetero is a global pharmaceutical company with a presence across multiple continents, specializing in API manufacturing and formulation development. Open Positions:1. Formulation Quality Control (QC) Executive2. Analytical Research &...
Bis Ethylhexyloxyphenol Methoxyphenyl Triazine Market Report Overview The Bis Ethylhexyloxyphenol Methoxyphenyl Triazine Market report provides a comprehensive and analytically structured examination of the Bis Ethylhexyloxyphenol Methoxyphenyl Triazine market. Based on rigorous primary and secondary research methodologies, it evaluates competitive dynamics, technological...
Comparing Polyclonal, Monoclonal, and Recombinant USP8 Validation Tools Laboratory workflows require distinct formulations of USP8 antibodies depending on whether researchers are conducting high-throughput screening, precise quantitative assays, or qualitative tissue imaging. Reagent manufacturers produce multiple formats—ranging from traditional polyclonal sera to advanced recombinant...
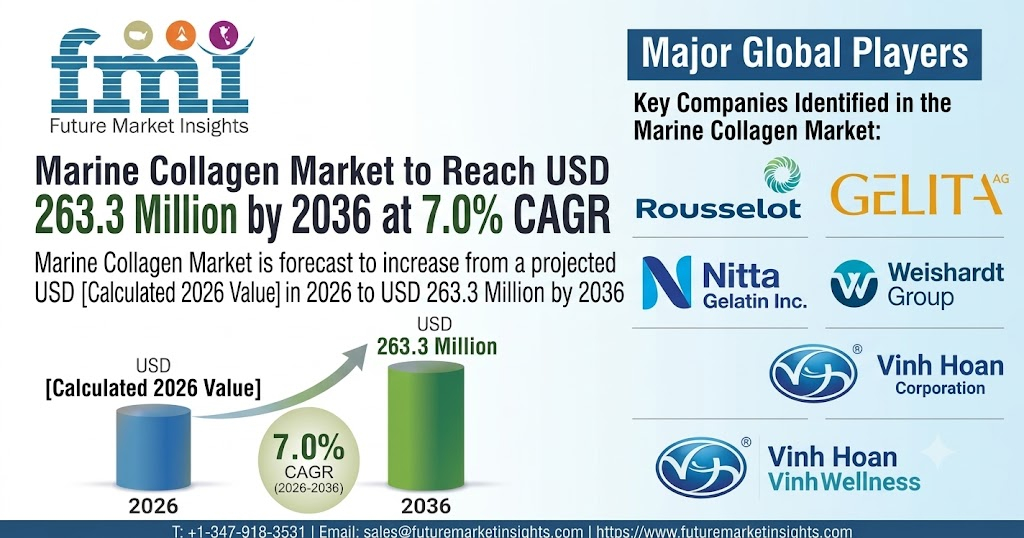
The global marine collagen market is estimated to reach USD 128.2 million in 2026 and is projected to reach USD 263.3 million by 2036, expanding at a 7.0% CAGR during the 2026-2036 forecast period, according to Future Market Insights. The market stood at USD 119.8 million in 2025. Growth is being supported by increasing demand for marine-derived collagen ingredients, greater focus on...