Term Life Insurance: How to Protect Your Family Without Overspending
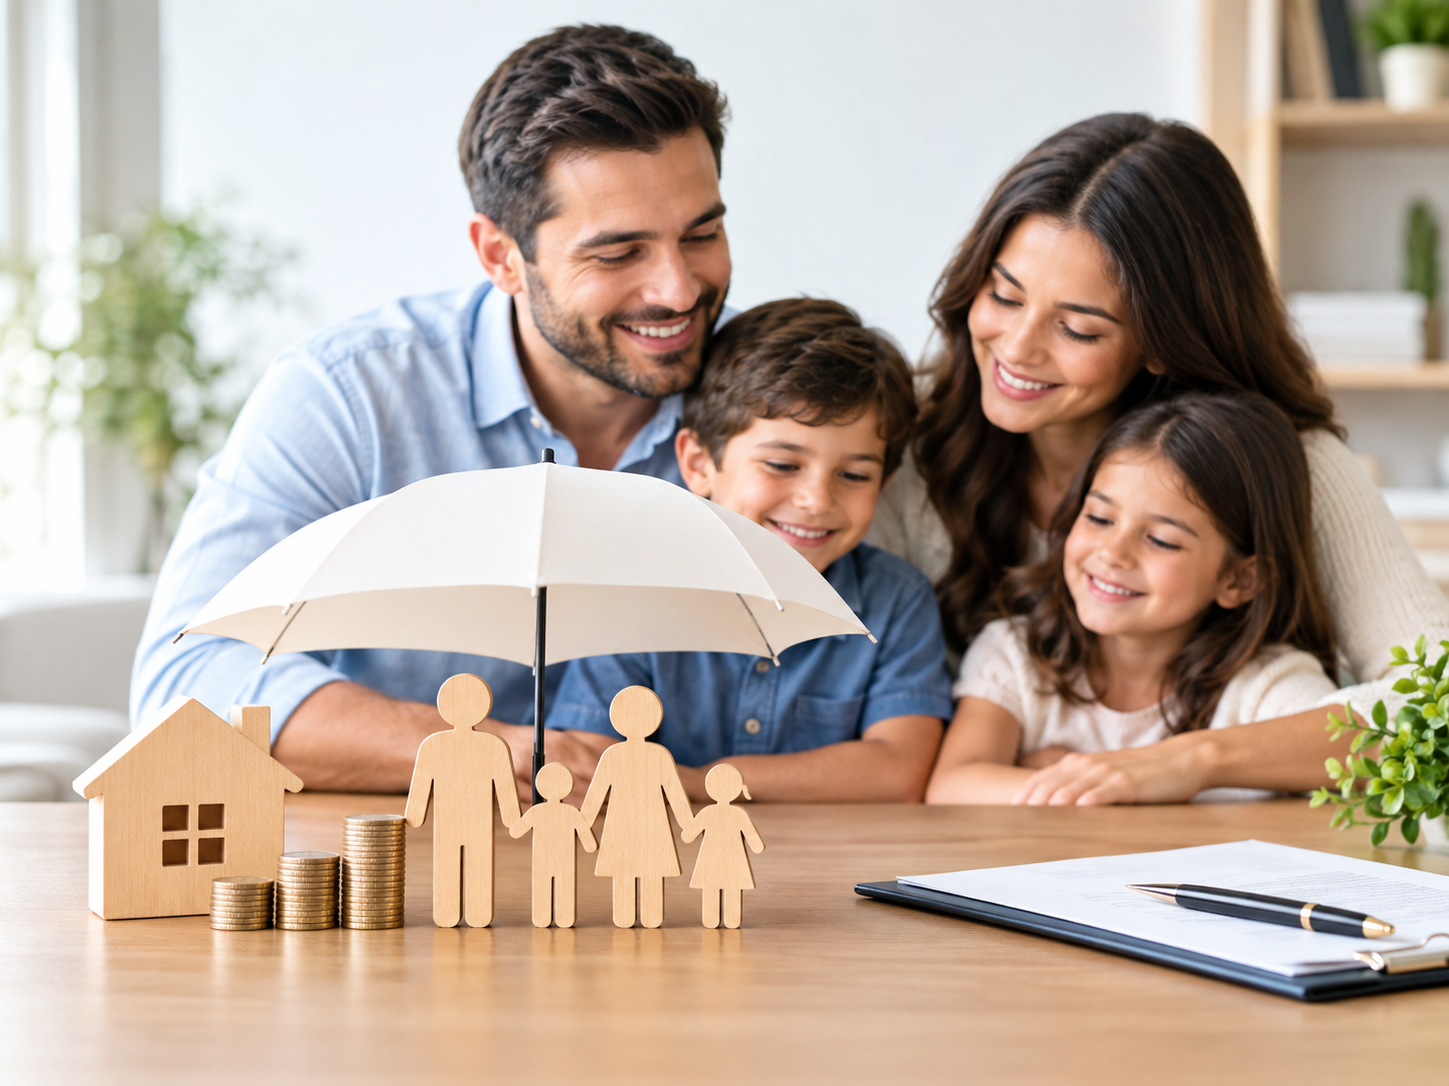
Protecting your family's financial future means preparing for unexpected events, not just planning for everyday expenses. If your family depends on your income to pay the mortgage, cover household bills, or fund your children's education, an unexpected loss could create serious financial challenges.
Term life insurance can help reduce this risk by providing financial support to your chosen beneficiaries if you pass away while the policy is active.
Unlike permanent life insurance, which may provide lifelong coverage and build cash value, term coverage is designed to protect you for a specific period. Common policy terms include 10, 20, and 30 years, although available options vary by insurer.
This makes term coverage worth considering for people who want financial protection during important stages of life, such as raising children, repaying a mortgage, or building long-term savings.
How Does Term Life Insurance Work?
A term policy is based on a straightforward agreement. You pay premiums according to the policy terms, and the insurer pays the agreed death benefit to your beneficiaries if you die while the coverage remains in force and the claim meets the policy requirements.
For example, imagine a parent purchases a $500,000 policy with a 20-year term. If the parent dies during those 20 years while the policy is active, the beneficiaries may receive the $500,000 death benefit, subject to the policy's terms and conditions.
The family could use the proceeds to replace lost income, pay outstanding debts, cover childcare expenses, or support future education costs.
However, if the insured person outlives the policy term, standard term coverage generally ends without a payout or cash value. Some policies offer renewal, conversion, or return-of-premium features, but these options may involve additional costs or specific conditions.
Understanding these details before purchasing a policy can help you avoid unexpected expenses later.
Why Do Families Choose Term Life Insurance?
Choosing the right coverage starts with identifying the financial risks your household would face if your income disappeared.
1. Replace Lost Household Income
If you are the primary earner, your salary may support nearly every part of your family's lifestyle. A death benefit can help surviving family members manage living expenses while adjusting to a new financial situation.
Consider your family's monthly spending, your spouse's income, and how long your dependents might need financial assistance. These details can help you estimate an appropriate coverage amount.
2. Protect Your Mortgage and Other Debts
Outstanding debts can become difficult to manage when household income falls. A life insurance payout may help your family continue making mortgage payments, repay personal loans, or settle other financial obligations.
You do not necessarily need coverage equal to every debt you owe. Instead, consider which obligations could place the greatest pressure on your family.
3. Support Your Children's Education
Education costs can continue for years, even if a parent's income is no longer available. Including future tuition, school fees, and related expenses in your coverage calculation may help protect your children's opportunities.
For parents with young children, a term that extends through their expected years of financial dependence may be worth considering.
4. Keep Protection Affordable
Term coverage often costs less initially than comparable permanent life insurance because it generally does not include a cash-value savings component.
This can allow households to obtain a larger death benefit for a given premium budget. Actual premiums depend on factors such as age, health, coverage amount, term length, and the insurer's underwriting requirements.
How Much Term Life Insurance Do You Need?
Choosing an appropriate coverage amount is one of the most important decisions you will make. Buying too little may leave your family exposed, while purchasing more coverage than necessary could strain your budget.
A practical starting point is to calculate your family's likely financial needs.
Step 1: Estimate future expenses. Add expected household living costs, education expenses, mortgage payments, other debts, and final expenses.
Step 2: Account for lost income. Estimate how much financial support your dependents may need and for how many years.
Step 3: Subtract available resources. Consider savings, existing life insurance, investments that could reasonably be used, and other dependable sources of income.
Step 4: Review the result. Compare the remaining financial gap with the coverage amounts available from insurers.
For example, suppose your family may need $600,000 to cover future living costs, education, and debts. If you have $150,000 in suitable savings and other available resources, the estimated gap is $450,000.
A $450,000 death benefit could be a starting point for further evaluation, not an automatic recommendation. Inflation, future expenses, taxes, investment returns, and your family's circumstances can affect the amount actually needed.
Term Life Insurance vs. Whole Life Insurance
Both policy types can provide a death benefit, but they serve different financial needs.
Term life insurance offers protection for a defined period and generally has no cash value. It may suit people seeking coverage during their working years or while dependents rely on their income.
Whole life insurance is designed to provide lifelong coverage as long as the policy remains in force under its terms. It typically builds cash value and usually requires higher premiums than comparable term coverage.
Neither option is best for every household. If your primary goal is to cover a mortgage or replace income for a limited period, term coverage may be a practical fit. If you need lifelong protection and value the policy's cash-value features, permanent coverage may deserve consideration.
Compare the premiums, benefits, flexibility, and long-term costs before deciding.
What Should You Check Before Buying a Policy?
Comparing insurance offers involves more than selecting the lowest advertised premium. A policy should fit your needs today and remain suitable for the period when your family needs protection.
Review these important details before applying:
-
Premium structure: Confirm whether premiums remain level throughout the initial term and what happens when the term ends.
-
Coverage duration: Choose a term that reflects your mortgage timeline, children's ages, and other financial responsibilities.
-
Renewal conditions: Find out whether renewal is available, how premiums may change, and whether age limits apply.
-
Conversion options: Check whether you can convert the policy into permanent coverage and when that option expires.
-
Exclusions and limitations: Read the contract carefully to understand the circumstances that could affect a claim.
-
Insurer reliability: Research the company's financial strength, reputation, claims process, and applicable licensing.
-
Beneficiary details: Name appropriate beneficiaries and review their information whenever your circumstances change.
Be honest on your application and read the policy documents before accepting coverage. Incorrect or incomplete information can create problems when a claim is reviewed.
How Financial Services Can Support Your Insurance Decision
Choosing protection is only one part of managing your family's finances. Your insurance decision should also fit your savings goals, retirement plans, debt obligations, and expected future expenses.
Professional financial services may help you evaluate these priorities together rather than treating each financial product as a separate decision.
For example, a financial professional may help you estimate how much income your family would need after your death, compare insurance options, and identify how premiums fit within your household budget.
You can also review how existing employer-provided coverage, emergency savings, and other assets affect your overall protection needs.
Before working with a financial or insurance professional, ask about their qualifications, compensation, services, and any potential conflicts of interest. Confirm whether they are appropriately licensed for the services they provide in your location.
The goal is not simply to purchase a policy. It is to build a financial plan that balances adequate protection with your other priorities.
Common Mistakes to Avoid When Choosing Term Coverage
A few common mistakes can reduce the value of an otherwise suitable policy.
Choosing a term that is too short: If your financial responsibilities continue after the policy expires, replacing coverage later may be more expensive or difficult to obtain.
Focusing only on price: A low premium is not enough if the policy has unsuitable terms, limited flexibility, or inadequate coverage.
Ignoring future affordability: Make sure you can maintain premium payments without neglecting essential expenses or emergency savings.
Forgetting to update beneficiaries: Marriage, divorce, births, and other major life events may require a beneficiary review.
Assuming coverage lasts forever: Standard term insurance ends at the end of its specified term unless a renewal or other continuation provision applies.
Cancelling existing coverage too early: If you replace a policy, wait until the new coverage is approved, issued, and in force before cancelling the existing policy, after carefully comparing both contracts.
Avoiding these mistakes can help you make a more informed decision and reduce the risk of a coverage gap.
When Should You Review Your Life Insurance?
Your insurance needs may change as your income, family responsibilities, and financial goals evolve. Review your coverage after major milestones, such as buying a home, having a child, changing jobs, or paying off significant debt.
It is also sensible to review your beneficiaries and policy conditions periodically. If your existing coverage no longer matches your financial responsibilities, compare available options before making changes.
Remember that applying for a new policy may involve medical underwriting, and your age or health could affect eligibility and premiums.
Conclusion
Term life insurance can provide valuable financial protection when your family depends on your income or faces significant long-term obligations. By selecting an appropriate coverage amount, choosing a suitable term, and understanding the policy's limitations, you can make a more confident decision.
Take time to compare policies, review your household budget, and consider how insurance fits into your broader financial plan. With careful preparation and informed guidance, you can protect your loved ones without committing to coverage that stretches your finances.
The right policy is one that addresses your family's genuine needs, fits your budget, and provides protection during the years it matters most.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
Metal additive manufacturing is moving beyond prototyping and becoming increasingly relevant to production environments. Improvements in printing speed, material quality, process monitoring, and design software are allowing manufacturers to create complex components with geometries that can be difficult to achieve through conventional machining, casting, or forging. The 3D Printing Metals...
The Mobile App Development Market size is witnessing extraordinary growth as organizations accelerate digital innovation and mobile-first business strategies worldwide. Mobile App Development Market Size was estimated at USD 94.4 Billion in 2024. The industry is projected to grow from USD 116.87 Billion in 2025 to USD 988.5 Billion by 2035, registering an impressive CAGR of 23.8%. The...
A defined body shape is often associated with balanced proportions, smooth contours, and improved confidence. However, certain areas may continue to store stubborn fat despite regular exercise and a healthy lifestyle. These localized fat deposits can affect the overall appearance of the body and make achieving desired contours challenging. Liposuction in Riyadh is an advanced body...
The Germany Dravet Syndrome Market has potential for continued development as Germany strengthens its focus on rare disease research and specialized neurological care. Dravet syndrome presents significant challenges because of its early onset and complex seizure patterns, creating an ongoing need for effective treatment and patient support. Research and innovation are expected to remain central...
Mongolia Buttermilk, dry Production is an important agricultural indicator that provides insight into the country's dairy processing and production landscape. Dry buttermilk is a dairy product obtained through the processing of buttermilk and can have applications across food manufacturing and ingredient supply chains. The Wantstats series covers the period from 2014 to 2023 and is based on...