How to Protect Your Business From Costly Jobsite Risks
Running a contracting business involves more than completing projects and keeping customers satisfied. Contractors face risks every day, from accidental property damage and workplace injuries to equipment theft and costly legal disputes. Even a small incident can interrupt operations, delay a project, and place pressure on your business finances.
Contractor insurance helps manage these risks by providing financial protection against covered losses. Whether you work in residential construction, commercial building, remodeling, electrical services, plumbing, or another trade, the right insurance coverage can help you operate with greater confidence.
Understanding your insurance options is an important step toward protecting your employees, equipment, projects, and professional reputation. Instead of choosing a policy based only on price, contractors should consider the specific hazards associated with their work, contractual requirements, and the financial impact of a potential claim.
What Is Contractor Insurance?
Contractor insurance is a general term for insurance policies designed to address the risks faced by construction professionals and independent contractors. Rather than being a single policy with identical benefits for every business, it can include several types of coverage based on the contractor's services, business structure, and operations.
For example, a general contractor managing multiple subcontractors may need different protection from an independent electrician who works primarily in residential properties.
A contractor insurance plan may include general liability insurance, workers compensation, commercial auto insurance, tools and equipment coverage, and commercial property insurance. Some projects may also require builders risk insurance or other specialized policies.
The purpose is to help contractors prepare for unexpected events without exposing their entire business to potentially significant financial losses.
Common Risks That Can Affect Contractors
Construction and contracting work involves physical activities, valuable equipment, customer properties, and multiple parties working together. These factors create several risks that business owners should consider.
Accidental Property Damage
A contractor may accidentally damage a customer's flooring during installation, break a window while working on an exterior wall, or cause damage to a nearby structure during construction. Depending on the circumstances and policy terms, general liability insurance may help cover eligible property damage claims.
Without appropriate coverage, the contractor may have to pay legal expenses, repair costs, or settlements out of pocket.
Workplace Injuries
Construction sites can expose workers to falls, heavy equipment, electrical hazards, and other workplace dangers. An employee injury can lead to medical expenses, lost wages, and work interruptions.
Workers compensation insurance may help provide benefits for covered workplace injuries and illnesses, subject to applicable state laws and policy requirements.
Theft or Damage to Tools
Professional tools, machinery, and equipment are essential to completing projects on time. Stolen power tools or damaged equipment can create unexpected replacement expenses and delay scheduled work.
Depending on the policy, tools and equipment coverage may help protect eligible items against covered theft or damage. Contractors should review where coverage applies, including whether equipment is protected while stored at a jobsite or transported between locations.
Vehicle Accidents
Contractors frequently travel between suppliers, offices, customer properties, and construction sites. An accident involving a work truck or van can create repair bills, liability claims, and business interruptions.
Commercial auto insurance can help address covered vehicle-related risks. Personal auto insurance may not provide the protection required for certain business uses, so contractors should discuss how their vehicles are used with an insurance professional.
Types of Contractor Insurance Coverage to Consider
Choosing the right insurance starts with understanding what each policy is intended to cover.
1. General Liability Insurance
General liability insurance is an important consideration for many contracting businesses. It generally addresses certain third-party bodily injury, property damage, and personal or advertising injury claims, depending on the policy.
For example, if a visitor is injured at a construction site or a contractor accidentally damages a client's property, this coverage may help with eligible claims and associated legal expenses.
General liability insurance does not cover every possible loss. It typically does not replace workers compensation, commercial auto, or professional liability coverage. Contractors should review exclusions, limits, and deductibles before purchasing a policy.
2. Workers Compensation Insurance
Workers compensation insurance helps provide benefits for covered employee work-related injuries and illnesses. Depending on applicable laws and the circumstances of a claim, benefits may include medical care and a portion of lost wages.
Requirements vary by state and can depend on factors such as the number of employees, business classification, and available exemptions. Contractors operating in Colorado should verify the rules that apply to their specific business rather than assuming that every independent contractor or small company follows the same requirements.
Appropriate coverage can help support injured workers while reducing the financial uncertainty associated with workplace accidents.
3. Commercial Auto Insurance
Commercial auto insurance is designed for vehicles used in business operations. It may provide liability protection and, when selected, coverage for physical damage to covered vehicles.
Contractors who transport tools, materials, or employees should evaluate how their vehicles are used and whether their policies reflect those activities.
The right policy depends on factors such as vehicle type, driving records, business mileage, and selected coverage limits.
4. Tools and Equipment Insurance
Replacing specialized tools can be expensive, particularly for businesses that depend on professional-grade equipment. Tools and equipment insurance may help cover eligible items damaged or stolen in covered circumstances.
Before purchasing coverage, prepare an inventory of your tools, machinery, and equipment. Record approximate values and keep receipts or photographs when possible.
Ask the insurer whether the policy covers rented equipment, newly purchased tools, items left in vehicles overnight, and equipment used at different jobsites. These details can make a meaningful difference when filing a claim.
5. Builders Risk Insurance
Builders risk insurance may help protect covered buildings and construction materials during a project. Coverage can vary based on the property, construction stage, policy wording, and selected endorsements.
This insurance may be relevant to contractors, property owners, developers, or other parties with an insurable interest in a construction project.
Review the project contract carefully to determine who must arrange coverage and what risks need to be addressed. Do not assume that a general liability policy covers damage to the building being constructed.
How to Choose Contractor Insurance That Fits Your Business
Buying insurance without assessing your business risks can leave important gaps in protection. A more practical approach is to evaluate your operations before requesting quotes.
Start by identifying the services you provide. Roofing contractors, electricians, plumbers, painters, and general contractors face different hazards. Your insurer needs accurate information about the work you perform, including any subcontracting arrangements.
Next, consider the size and value of your projects. A contractor working on large commercial properties may face different liability exposures and contract requirements from someone completing small residential repairs.
Review your equipment, vehicles, workforce, and business property. Consider which assets would be difficult to replace and how long your company could continue operating after a major loss.
Finally, examine your contracts. Clients, property managers, and general contractors may require specific insurance limits, certificates of insurance, or additional insured endorsements. Confirm that the policy satisfies those requirements before work begins.
An experienced insurance professional can help compare options and explain the differences between policies, exclusions, deductibles, and coverage limits.
How Contractors Can Manage Insurance Costs
Insurance premiums are an important business expense, but selecting the cheapest policy is not always the most cost-effective decision. A policy with inadequate limits or major exclusions may leave your company exposed to expenses that exceed any initial savings.
Contractors can take several practical steps to manage costs while maintaining suitable protection.
-
Maintain a safe workplace: Provide appropriate training, use required protective equipment, and establish clear jobsite safety procedures.
-
Keep accurate records: Document employee information, payroll, subcontractor agreements, equipment purchases, and business activities.
-
Compare coverage carefully: Request quotes with comparable limits, deductibles, and policy terms instead of comparing prices alone.
-
Review your coverage annually: Update your insurer about new services, additional employees, larger projects, and newly purchased equipment.
-
Reduce preventable losses: Secure tools, maintain vehicles, inspect equipment, and follow relevant safety standards.
-
Ask about available discounts: Some insurers may offer savings for eligible safety measures, policy combinations, or other qualifying factors.
These steps can help insurers evaluate your business more accurately and may improve your ability to obtain competitive coverage.
Why Contractor Insurance Is Important in Colorado
Contractors working in Colorado should consider the risks associated with their trade, project locations, business vehicles, and contractual responsibilities. Construction businesses may work on residential properties, commercial developments, renovations, and outdoor projects, each with its own exposures.
Colorado workers compensation requirements should be reviewed based on the business's workforce and circumstances. Contractors should also confirm whether project owners or general contractors require particular liability limits or proof of coverage before allowing work to begin.
Weather-related events, property damage, equipment theft, and vehicle accidents can affect operations, but the availability of protection depends on the policy and applicable exclusions.
For businesses serving Colorado customers, reviewing contractor insurance with a knowledgeable professional can help identify coverage gaps and build a plan that reflects actual business needs.
What to Check Before Buying a Policy
Before choosing an insurance policy, make sure you understand the details that determine how it responds to a claim.
Check the policy limits to see the maximum amount available for covered losses. Review the deductible, which is the amount you may need to pay before certain coverage applies. Read the exclusions carefully, particularly those involving specific trades, subcontractors, completed operations, or particular types of property damage.
You should also confirm whether coverage applies to all the locations where you work and whether your insurer has accurate information about your services.
Ask how claims should be reported and what documentation may be required. Keeping contracts, photographs, receipts, maintenance records, and incident reports organized can make the claims process easier.
Most importantly, request clarification whenever a coverage term is unclear. Written confirmation of important coverage details can help you make a more informed decision.
Final Thoughts
Contracting businesses face risks that can affect their finances, employees, equipment, and ability to complete projects. The right contractor insurance strategy can help manage covered losses and support greater business stability.
By understanding general liability, workers compensation, commercial auto, tools and equipment, and builders risk coverage, contractors can make more informed choices about protecting their operations.
Start by assessing your actual risks, reviewing contractual obligations, and comparing policies with similar coverage limits. A well-matched insurance plan can help you prepare for unexpected setbacks while keeping your attention on delivering quality work and building lasting customer relationships.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
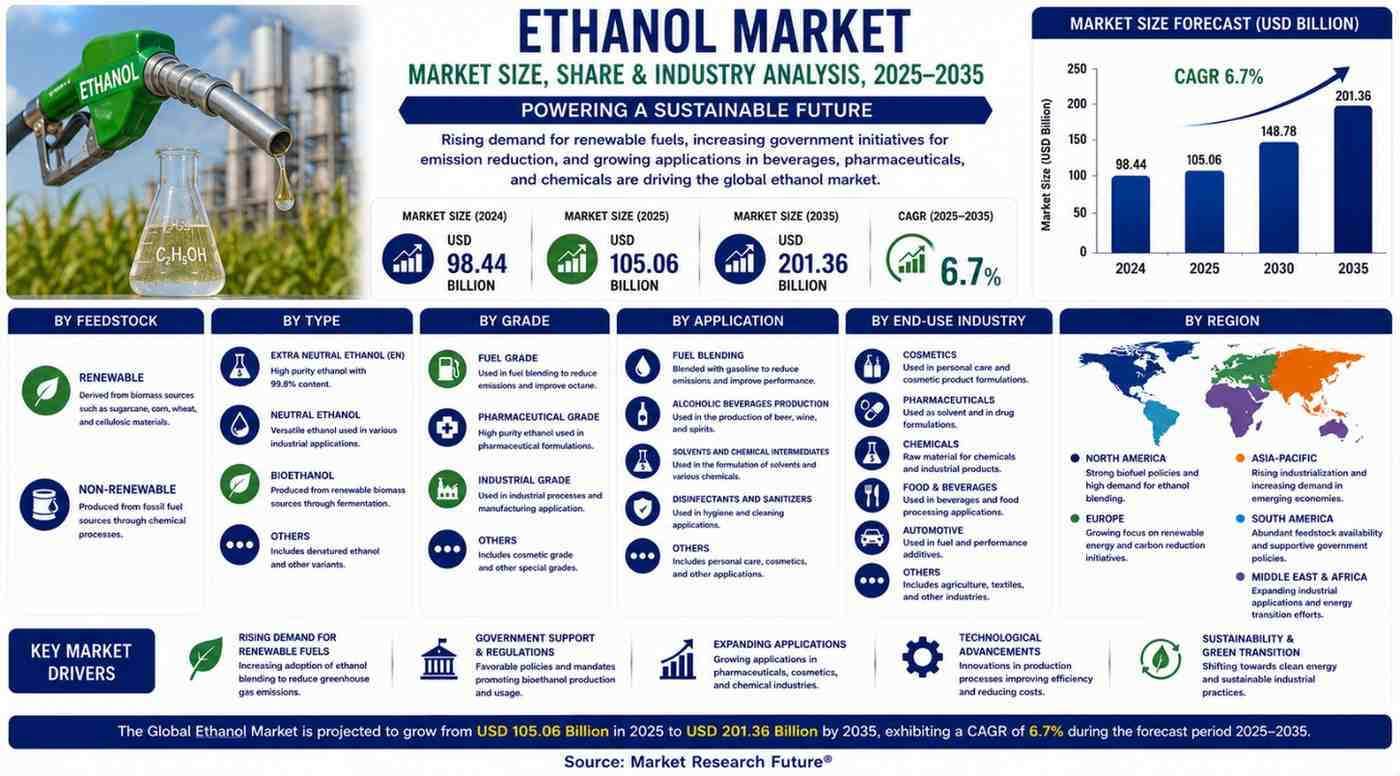
According to Market Research Future®, the Ethanol Market was valued at USD 98.44 billion in 2024 and is projected to grow from USD 105.06 billion in 2025 to USD 201.36 billion by 2035, exhibiting a compound annual growth rate (CAGR) of 6.72% during the forecast period (2025–2035). Rising demand for renewable transportation fuels, expanding ethanol blending mandates, and increasing...
The UK Non Alcoholic Steatohepatitis Biomarkers Market is emerging as a significant area of opportunity within liver diagnostics, supported by rising disease awareness, advances in biomarker discovery, and demand for improved monitoring solutions. Market Research Future reports that the market is expected to grow from USD 9.46 million in 2025 to USD 96.92 million by 2035, at a CAGR of 26.19%...
The growing awareness of contamination risks in biopharmaceuticals underscores a pivotal shift in the market dynamics of host cell contaminant testing. According to , the Host Cell Contaminant Testing Market is projected to reach $0.616 billion by 2035, evolving at a CAGR of 6.48%. This growth reflects an increasing need for stringent testing protocols as regulatory bodies enforce compliance...
Introduction! The growth of online entertainment has changed the way people follow sports and access digital gaming services. Today, users can explore sports markets, live events, and various online games through mobile phones and computers. Laser247 is a name commonly associated online with sports betting and gaming services, particularly cricket and other popular sporting events. Before using...
The Intramuscular HPV Vaccination Market is expanding as governments, healthcare organizations, and pharmaceutical companies increase efforts to prevent human papillomavirus (HPV) infections and HPV-associated cancers. According to WiseGuyReports, the market was valued at approximately USD 6.6 billion in 2024 and is projected to reach USD 12.0 billion by 2035, representing a CAGR of...