OEM Insulation Market to Reach US$43.1 Billion by 2032 as Energy Efficiency Drives Industry Demand
Market Overview and Growth Outlook
The global OEM insulation market was valued at US$31.5 billion in 2023 and is projected to reach US$43.1 billion by 2032, reflecting sustained demand for insulation materials across major manufacturing and construction industries.
The OEM insulation market is expected to grow at a CAGR of 5.6% during 2024–2032.
Growth is supported by increasing energy efficiency requirements, environmental sustainability initiatives, and expanding demand from construction, automotive, industrial, and consumer applications.
Original equipment manufacturers increasingly require insulation materials that improve thermal performance, manage heat, reduce noise, and support energy conservation. These requirements are strengthening demand for specialized insulation solutions.
The industry's long-term development reflects a broader emphasis on energy-efficient equipment, buildings, and transportation systems.
An assessment of OEM insulation market trends reveals how energy efficiency requirements are influencing insulation material selection across multiple industries. The growing adoption of electric vehicles, energy-efficient appliances, and sustainable construction materials reinforces demand for improved thermal performance. Together, these developments explain why manufacturers are incorporating lightweight and high-performance insulation solutions into products and systems that require effective temperature management and energy conservation.
Request a free sample report: https://www.stratviewresearch.com/Request-Sample/oem-insulation-market#form
Market Segmentation Analysis
The OEM insulation market is categorized by Types into Mineral Wool, Polyurethane Foam, Flexible Elastomeric Foam, and Other Insulations.
Among these categories, Polyurethane Foam is expected to experience significant growth due to its excellent thermal insulating properties. Its low thermal conductivity and lightweight characteristics support applications in building insulation, refrigeration, and automotive systems.
By End Use, the market includes Building & Construction, Industrial, Transportation, and Consumer.
Building & Construction is expected to continue growing as urbanization increases demand for residential, commercial, and industrial buildings. The growing emphasis on sustainable building materials and energy-efficient construction also supports the adoption of advanced insulation solutions.
These segments demonstrate how insulation demand is influenced by material performance requirements and the operating conditions of different end-use industries.
Regional Market Insights
North America: Largest Market Share
North America holds the largest share of the OEM insulation market, supported by its well-developed construction and automotive industries. The USA represents the largest country-level market, reflecting the importance of its advanced construction and automotive sectors in regional insulation demand.
Asia-Pacific: Significant Growth Opportunities
Asia-Pacific is expected to experience significant growth, driven by infrastructure development and increasing urbanization. Expanding construction activity across residential, commercial, and industrial facilities supports demand for insulation materials. The region's automotive manufacturing industry and increasing electric vehicle production further reinforce demand for thermal insulation solutions.
Emerging Trends Shaping the OEM Insulation Market
Energy conservation is becoming an increasingly important factor in insulation material selection. Stricter energy efficiency regulations are supporting demand for materials with strong thermal performance.
The shift toward sustainable construction is another important industry trend. Manufacturers and building developers are emphasizing insulation materials that support energy-efficient structures and environmental objectives.
Electric vehicle adoption is also influencing market development. Growing EV production increases demand for thermal insulation materials used in automotive applications.
Recent product developments highlight the industry's material innovation. In 2023, Dow Chemical introduced a bio-based polyisocyanurate insulation product designed to reduce environmental impacts while maintaining insulation efficiency.
These developments illustrate how insulation performance, material innovation, and sustainability objectives are shaping the industry's direction.
Key Growth Drivers of the Market
- Rising energy efficiency requirements: Increasing energy conservation standards encourage manufacturers to adopt insulation materials that reduce energy consumption and improve thermal performance.
- Expansion of construction activities: Urbanization increases residential, commercial, and industrial building development, creating additional demand for insulation products.
- Growing electric vehicle adoption: Increasing EV production strengthens demand for advanced thermal insulation solutions within automotive manufacturing.
- Greater emphasis on environmental sustainability: Green building initiatives and sustainable material requirements encourage the adoption of energy-efficient insulation solutions.
- Demand for high-performance insulation: Requirements for heat resistance, noise reduction, and lightweight materials support insulation adoption across manufacturing industries.
Competitive Landscape
The OEM insulation market is highly fragmented, with more than 500 players competing across the industry. Competition is influenced by pricing, service offerings, and regional presence.
Top Companies in the Market
- Johns Manville
- Knauf Insulation
- Saint-Gobain
- Rockwool International A/S
- Owens Corning
- Armacell International S.A.
- Aspen Aerogels, Inc.
- Kingspan Group
- Huntsman Corporation
- Covestro AG
Conclusion and Strategic Outlook
The OEM insulation market is forecast to reach US$43.1 billion by 2032, growing at a CAGR of 5.6%.
Increasing energy efficiency requirements, sustainable construction practices, and electric vehicle manufacturing are supporting the industry's long-term growth trajectory.
Polyurethane Foam represents an important material growth category, while Building & Construction remains a key source of expanding demand. North America maintains the largest market share, and Asia-Pacific offers significant growth opportunities.
The industry outlook reflects continuing demand for insulation materials that combine thermal performance, energy conservation, and application-specific functionality.
FAQs – OEM Insulation Market
1. What is the current size and future forecast of the OEM insulation market?
The OEM insulation market was valued at US$31.5 billion in 2023. It is forecast to reach US$43.1 billion by 2032.
2. What is the expected CAGR of the OEM insulation market?
The OEM insulation market is projected to expand at a CAGR of 5.6% during 2024–2032. Growth is supported by energy efficiency requirements and increasing industrial demand.
3. What factors are driving OEM insulation market growth?
Major drivers include energy-efficient construction, urbanization, sustainable materials, and electric vehicle production. Demand for improved thermal management and acoustic performance also supports market expansion.
4. Which regions are important for OEM insulation demand?
North America holds the largest market share, supported by established construction and automotive industries. Asia-Pacific is expected to experience significant growth due to infrastructure expansion, urbanization, and automotive manufacturing.
5. What does the investment outlook indicate for the OEM insulation market?
The forecast indicates continued opportunities in energy-efficient insulation materials and expanding end-use applications. A fragmented competitive landscape makes pricing, service offerings, and regional presence important considerations for market participants.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
Growing emphasis on patient-centered care, self-administration, and improved treatment adherence is driving the evolution of the GCC Pen Injectors industry. According to Business Market Insights, the GCC Pen Injectors Market is projected to grow steadily, reaching US$ 52.1 million by 2033 from US$ 38.6 million in 2025. The market is expected to record a CAGR of 3.8% over the forecast period...
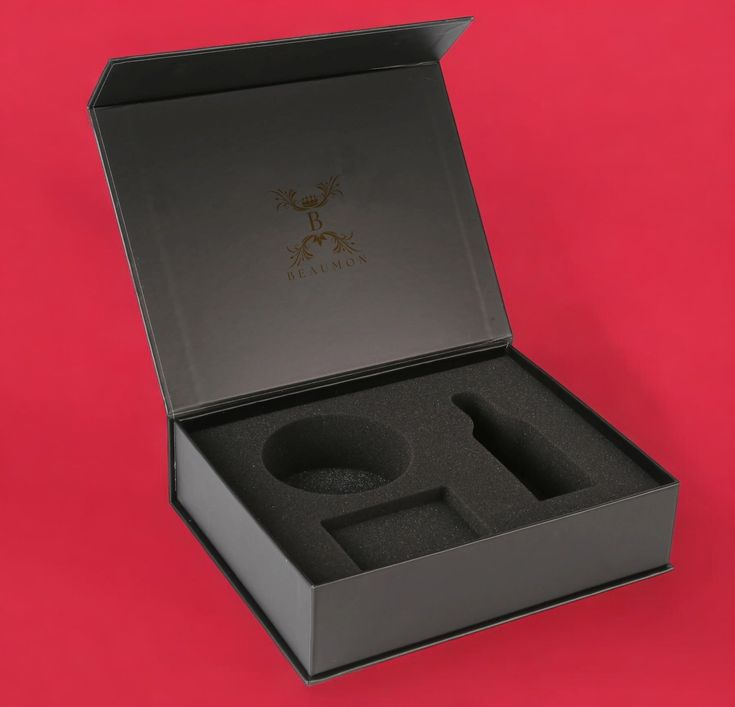
Learn how custom rigid boxes with inserts protect your products and improve your brand presentation with simple, sturdy, and clean design options. First impressions matter a lot when you open a package. Standard cardboard boxes often fail to protect your items well. Many brands now use custom rigid boxes with inserts to keep things safe. These sturdy packages provide a great way to display your...
According to a new report from Intel Market Research, the global Semiconductor Back-End Process Equipment market was valued at USD 10,960 million in 2025 and is projected to reach USD 19,770 million by 2034, growing at a robust CAGR of 9.0% during the forecast period (2026–2034). This expansion is driven by surging demand for advanced packaging solutions in high‑performance computing, the...
The nanocomposites market is witnessing strong growth driven by rising demand for lightweight, high-performance materials across industries such as automotive, aerospace, electronics, packaging, and healthcare. Nanocomposites are engineered by incorporating nanoscale reinforcements into a matrix material, significantly enhancing properties such as strength, thermal stability, barrier...
Finding dependable domestic help can make everyday life much easier, especially for families managing work, children, elderly parents, and household responsibilities at the same time. In a busy city like Bengaluru, many households need reliable support for cleaning, cooking, childcare, elderly assistance, and routine household work. However, choosing the right person is not simply about finding...