B2B Digital Payment Management Share Reflects Innovation in Business Payment Services
Market Overview
The B2B Digital Payment Management share is influenced by innovation in business payment services and the growing demand for integrated financial workflows. Payment providers, financial technology companies, banks, and enterprise software vendors offer tools for managing commercial transactions. Their solutions may cover invoice payments, corporate spending, supplier settlements, digital wallets, and transaction reconciliation. Businesses compare providers based on transaction reliability, security, payment options, pricing transparency, and compatibility with existing systems. The ability to support different industries and organizational sizes can also affect customer choice. As businesses modernize their financial operations, providers are working to make payment processes more connected and easier to manage. Competitive performance increasingly depends on combining efficient technology with dependable service and practical business functionality.
Innovation in Payment Services
Innovation is expanding the range of capabilities available to businesses. Integrated payment tools can connect invoice processing with authorization, settlement, and reconciliation. Application programming interfaces help platforms exchange information with accounting software and enterprise resource planning applications. Digital wallets and corporate card tools can support particular purchasing needs, while bank transfers remain important for many supplier transactions. Some providers offer international payment features for companies working with overseas partners. These services must account for differences in currency, payment infrastructure, and regulatory obligations. Businesses should compare options according to their actual transaction patterns and supplier preferences. A payment method that works well for one workflow may not be appropriate for every supplier or business unit.
Trust, Security, and Integration
Trust is essential in business payments because transaction errors and fraud can affect supplier relationships and financial operations. Providers may use encryption, authentication, tokenization, and transaction monitoring to help protect payment information. Organizations also need internal controls for supplier onboarding, bank-detail changes, and payment approvals. Integrating payment platforms with accounting systems can reduce manual recordkeeping and make reconciliation easier, but poorly configured connections may introduce errors. Companies should test integrations, maintain clear access permissions, and establish procedures for resolving failed transactions. Reliable support and clear documentation can further improve the user experience. Providers that make security and integration practical parts of their service may be more attractive to businesses seeking dependable financial technology.
Competitive Outlook
The competitive environment may increasingly favor platforms that connect payment execution with broader financial operations. Businesses may seek consolidated tools for invoicing, approval management, supplier payments, reconciliation, and reporting. Providers can differentiate themselves through usability, integration depth, support for different transaction methods, and capabilities for cross-border commerce. New technologies may improve monitoring and workflow automation, but their adoption should remain aligned with business requirements. Buyers should evaluate providers through practical demonstrations and confirm that advertised capabilities meet operational needs. Strong governance and clear service expectations can help organizations maintain control as their payment activities become more digital. Innovation will be most valuable when it makes business transactions more transparent, reliable, and manageable.
Explore Our Latest Trending Reports!
Marketing Automation Platform Market
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
Escort girls in Lahore are undoubtedly the ideal choice for their clients. As the most authentic and self-assured Hot call girls in Lahore, they have earned the highest praise from their clients. The best way for a girl to satisfy and delight her clients is to be dedicated and professional. That's why our agency is known for providing our clients with the perfect girl, the perfect friend, and...

Edge AI hardware comprises advanced computing components specifically engineered to execute artificial intelligence and machine learning workloads directly on edge devices, close to where data is generated. These hardware solutions include AI processors, neural processing units (NPUs), AI accelerators, memory modules, storage devices, connectivity components, and embedded systems that support...
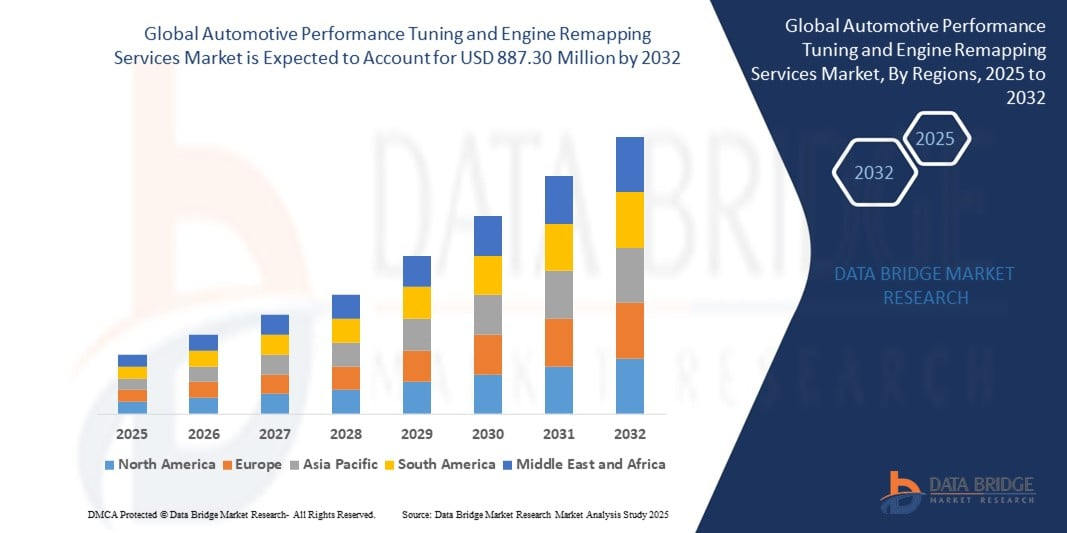
According to the latest report published by Data Bridge Market Research, the Automotive Performance Tuning and Engine Remapping Services Market The global automotive performance tuning and engine remapping services market size was valued at USD 571.19 million in 2024 and is expected to reach USD 887.30 million by 2032, at a CAGR of 5.66% during the...
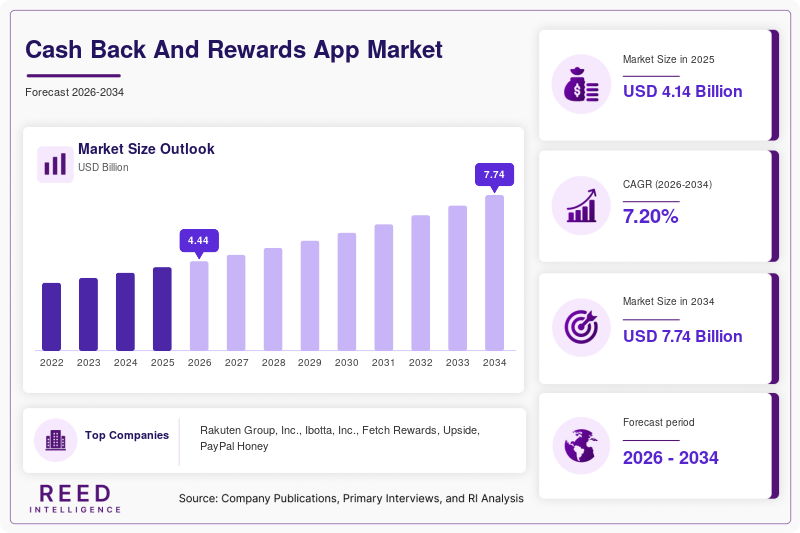
Cash Back and Rewards App Market Size, Share, Demand, Growth & Forecast 2026–2034 Market Overview The Cash Back and Rewards App Market is evolving from simple coupon-distribution tools into transaction platforms connecting consumers, retailers, brands, payment providers, and affiliate networks. The market enables participating merchants and brands to convert consumer purchase activity...
According to the latest report published by Data Bridge Market Research, the Ependymoma Treatment Market The Global Ependymoma Treatment Market size was valued at USD 151.33 million in 2024 and is expected to reach USD 225.29 million by 2032, at a CAGR of 5.1% during the forecast period. The persuasive Ependymoma Treatment Market report covers...