The Great Balancing Act: How the China Renewable Energy Storage Market is Anchoring the Global Energy Transition
The global narrative of the twenty-first century is being written in the language of energy. As nations race to decarbonize their economies, the primary challenge has shifted from merely generating clean electricity to managing its inherent volatility. Sun and wind do not follow the rhythms of human demand, creating a desperate need for a "buffer" that can store vast amounts of power for use at a moment's notice. In this high-stakes arena, the china renewable energy storage market has emerged as the world’s most significant laboratory and its most prolific factory. By integrating aggressive state-level mandates with a hyper-competitive manufacturing ecosystem, the nation has moved beyond the experimental phase to a state of absolute industrial dominance, ensuring that its massive renewable expansion is backed by the world’s most resilient storage infrastructure.
The Strategic Necessity of Storage
China’s journey into energy storage is born of necessity. The country is home to the world’s largest fleet of wind and solar farms, much of which is located in the sparsely populated, sun-drenched, and wind-swept regions of the northwest. However, the vast majority of the country’s energy consumption occurs thousands of miles away in the industrial megacities of the eastern coast.
Without storage, the electricity generated in the desert often goes to waste because it exceeds the capacity of the transmission lines or the immediate needs of the grid. This phenomenon, known as curtailment, was the primary catalyst for the storage boom. To solve this, the government implemented "mandatory storage" policies, requiring new renewable projects to build or lease storage capacity equal to a percentage of their total output. This top-down approach has turned energy storage into a foundational requirement for doing business in the Chinese energy sector.
A Spectrum of Technologies: Beyond Lithium-Ion
While lithium-ion batteries, specifically Lithium Iron Phosphate (LFP), are the workhorses of the current market due to their safety and cost-efficiency, the Chinese market is characterized by a deliberate push toward technological diversity. The goal is to build a "multi-layered" storage system that can handle different time horizons.
-
Pumped Hydro Storage (PHS): This remains the bedrock of the national strategy. China is currently building massive "gravity batteries"—reservoirs at different elevations that move water to store and release energy. This technology provides the long-duration, large-scale stability that chemical batteries cannot yet match.
-
Compressed Air Energy Storage (CAES): Several gigawatt-scale projects are now utilizing abandoned salt caverns to store energy in the form of high-pressure air. When the grid needs power, the air is released to spin turbines, providing a reliable long-duration solution.
-
Flow Batteries: In 2026, we are seeing a significant surge in vanadium redox flow battery installations. These systems are ideal for stationary grid storage because they offer almost unlimited cycle life and carry no risk of thermal runaway, making them the preferred choice for massive urban storage hubs.
-
Sodium-Ion Breakthroughs: To reduce reliance on expensive lithium imports, the domestic market is pioneering sodium-ion batteries. Using abundant salt-based materials, these batteries are becoming the low-cost alternative for the next generation of utility-scale projects.
The Rise of Shared and Standalone Storage
A major evolution in the market is the shift from "co-located" storage to "shared" or "shared-merchant" storage. In the early days of the boom, every solar farm had its own small battery pack. Today, the trend is toward massive, independent storage plants that act as a utility for the entire region.
These standalone facilities, often reaching capacities of hundreds of megawatts, operate on a shared model. A renewable energy developer can "rent" capacity from these plants to meet their regulatory requirements, while the storage plant operator can earn additional revenue by participating in the electricity spot market. This model improves the economic efficiency of storage, as these large-scale facilities can provide ancillary services like frequency regulation and peak shaving more effectively than many smaller, isolated units.
Supply Chain Supremacy and Innovation Cycles
The dominance of the Chinese market is underpinned by a level of vertical integration that international competitors find difficult to replicate. From the processing of raw minerals to the manufacturing of cells and the final assembly of containerized systems, the domestic supply chain is a closed loop of efficiency.
This integration allows for incredibly fast innovation cycles. When a new chemical refinement or a more efficient cooling system for battery containers is developed, it can be implemented across the manufacturing base in months rather than years. This "fast-follower" and "mass-innovator" approach has driven the cost of storage systems down to levels that were once thought impossible, making grid-scale storage economically viable without heavy, long-term subsidies.
Regional Dynamics: The Power Silk Road
The geographical distribution of these storage projects is a masterclass in strategic planning. The provinces of Xinjiang, Inner Mongolia, and Gansu have become the primary theaters for storage expansion. These regions serve as the "power plants" for the rest of the country.
By placing massive battery and pumped hydro installations at the head of Ultra-High Voltage (UHV) transmission lines, the grid operator can ensure a steady, "smoothed" flow of electricity to the east. This reduces the stress on the transmission infrastructure and ensures that the coastal megacities are powered by 100% green energy, even when the wind isn't blowing in the desert.
The Path to 2060: A Carbon-Neutral Grid
As China moves toward its "Dual Carbon" goals—peaking emissions before 2030 and reaching carbon neutrality by 2060—the renewable energy storage market is the indispensable enabler. The ultimate goal is to transition the national grid from one dominated by coal to one centered on renewables.
In 2026, the market has moved beyond just "balancing" the grid; it is beginning to replace the role of traditional gas-peaker plants. Every gigawatt of storage added is a step toward decoupling economic growth from carbon emissions. The success of this market proves that a high-penetration renewable grid is not just a dream, but a practical, industrial reality.
Conclusion
The China renewable energy storage market is the engine room of the global energy transition. Through a combination of massive industrial scale, technological diversification, and visionary market design, the country has turned the challenge of renewable intermittency into a massive economic and strategic opportunity. As the rest of the world watches, the innovations and cost reductions pioneered in China today are defining the global standards for how a modern, green economy powers itself. The future of energy is no longer just about how we catch the wind or the sun, but about how we hold onto it for the moments we need it most.
Gain valuable insights through comprehensive industry analysis:
instrument transformer equipment corp
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
The global property insurance market is experiencing a notable transformation, with its size projected to reach USD 492.65 billion by 2035, reflecting a solid growth trajectory. This growth comes on the heels of a compound annual growth rate (CAGR) of 5.6%, signaling robust demand driven by a complex interplay of environmental, social, and economic factors. The evolving risk landscape,...

The concept of knowing exactly where food comes from and how it reaches the plate is no longer a niche preference—it is a mainstream expectation. Farm-to-Fork Traceability embodies this ideal by creating an unbroken information chain that connects agricultural origins with final consumption. As per Market Research Future, the emphasis on complete journey tracking is intensifying...
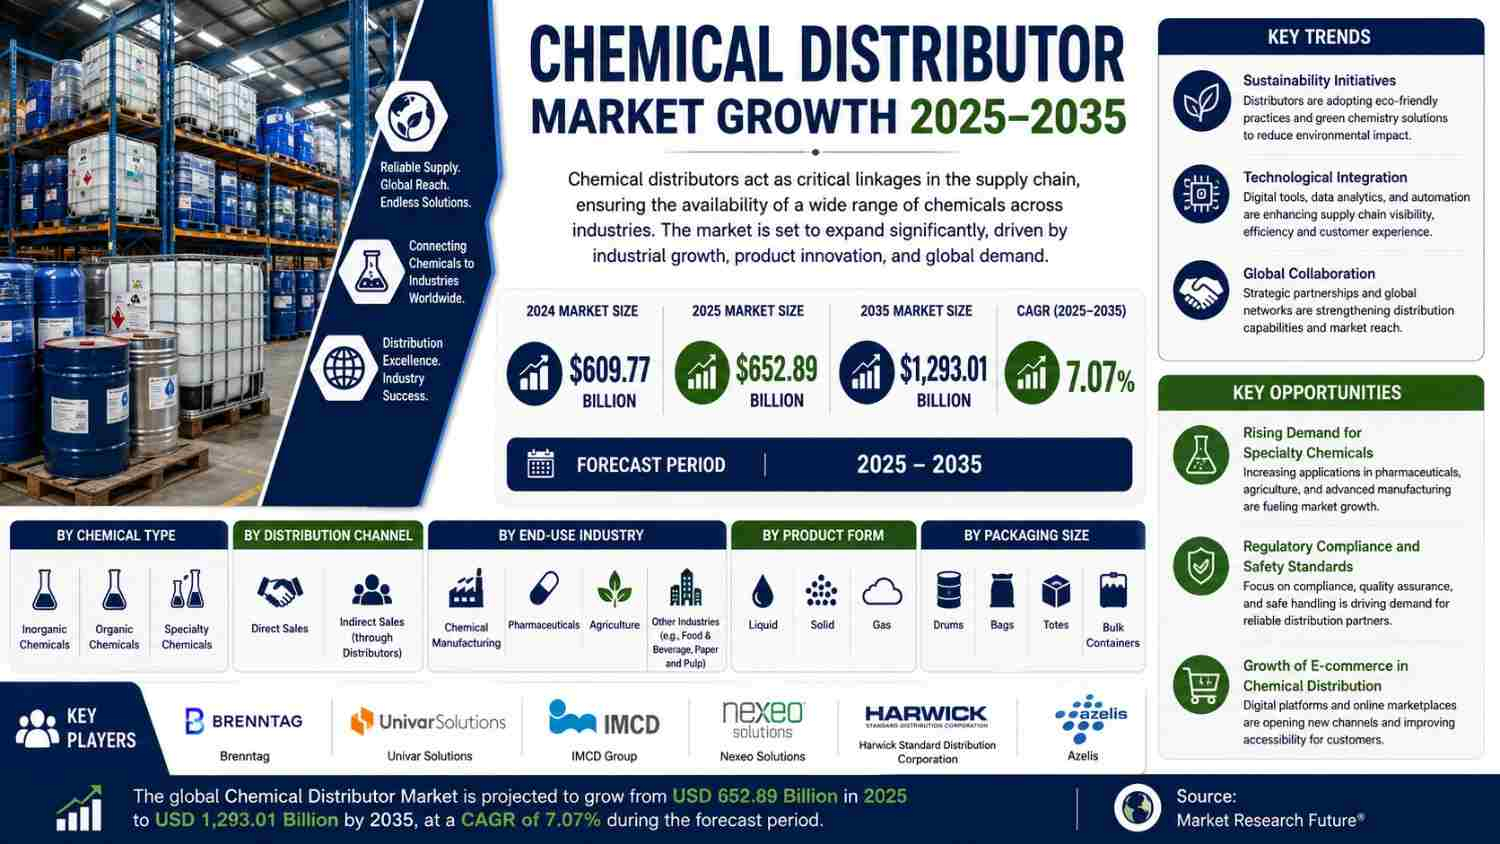
Chemical Distribution Is Becoming a Strategic Part of Industrial Supply Chains The chemical industry depends on more than production capacity. Manufacturers also need the right materials delivered in the right form, quantity, packaging and compliance framework, often across complex international supply networks. The Chemical Distribution Market was valued at USD 609.77 billion in 2024 and...
Healthy skin depends on consistent cleansing, but not all cleansing methods work the same way. Many people wash their face daily and assume that is enough to keep their skin clear. However, pollution, makeup residue, oil buildup, and dead skin cells often remain trapped inside the pores. This is why treatments like Deep skin cleansing in Riyadh (تنظيف بشرة) are becoming more popular...

The continuous technological evolution in molecular diagnostics acts as the primary engine propelling the Liquid Biopsy Market. At the core of this progress is Next-Generation Sequencing (NGS), which allows parallel sequencing of millions of DNA fragments. NGS-based liquid biopsies provide comprehensive genomic profiling, enabling clinicians to identify single nucleotide variants, insertions,...