India Flexible Packaging Market Opportunities in Tier-2 and Tier-3 Cities
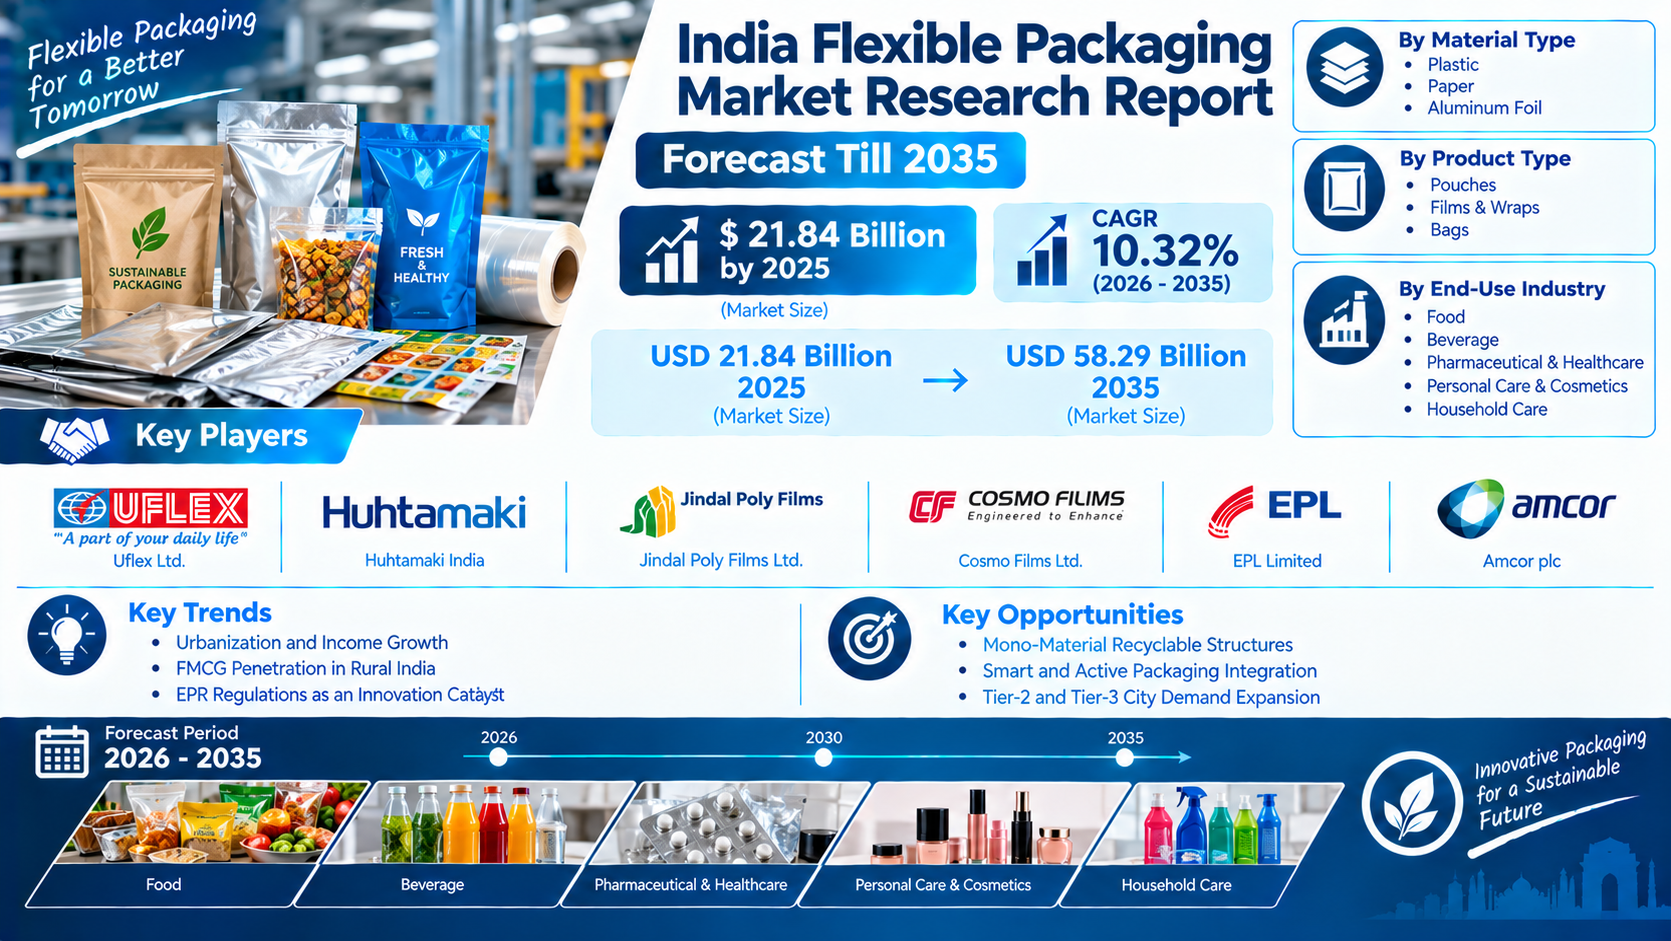
According to Market Research Future® (MRFR), the India Flexible Packaging Market is expected to increase from USD 21.84 billion in 2025 to USD 58.29 billion by 2035, representing a compound annual growth rate (CAGR) of 10.32% over the 2026–2035 forecast period. Flexible packaging serves manufacturers across consumer goods and healthcare industries by providing adaptable formats for product containment, protection, storage, and distribution. India's changing consumption patterns, increasing FMCG availability in rural areas, and evolving sustainability expectations are creating new requirements for packaging suppliers. Material innovation, smart packaging integration, and demand growth in Tier-2 and Tier-3 cities are additional areas of opportunity.
Changing Consumer Markets and Packaging Requirements
Flexible packaging is used across a wide range of products because it can be manufactured in different shapes, sizes, and material combinations. Pouches, films and wraps, and bags support applications ranging from everyday consumer goods to products with more specific handling and protection requirements. For manufacturers, packaging decisions affect product presentation, storage, transportation, and the consumer's experience when opening or using a product.
Urbanization and income growth are identified as significant market trends. As consumer purchasing patterns change, companies may adjust their product portfolios and packaging formats to suit different usage occasions and retail channels. Packaging must address practical requirements while also supporting brand presentation and convenient product handling. Flexible formats provide manufacturers with a range of design possibilities, although the most suitable option depends on the product and its distribution conditions.
FMCG penetration in rural India is another important influence. Broader availability of packaged consumer goods can expand the potential customer base for packaging manufacturers. Companies serving rural markets may need formats that fit their distribution models, product positioning, and target consumers. Packaging requirements can vary between product categories, making flexibility in format selection important for suppliers serving multiple brands and applications.
Material Choices and Product Formats
The market is divided into plastic, paper, and aluminum foil by material type. Each category offers different characteristics, and material selection must account for product protection, packaging performance, processing requirements, and end-use conditions. Manufacturers also need to consider applicable regulations and sustainability expectations when evaluating materials.
Plastic is used across numerous flexible packaging applications, while paper offers an alternative for products and formats suited to its characteristics. Aluminum foil may be selected where specific barrier properties are needed. These materials are not interchangeable in every application; their suitability depends on the performance requirements of the product and the packaging structure.
Product segmentation covers pouches, films and wraps, and bags. Pouches can accommodate different package designs and product categories. Films and wraps serve wrapping and containment requirements, while bags provide a flexible format for packaging and carrying goods. Each category supports distinct applications across food, beverages, healthcare, personal care, cosmetics, and household care.
Packaging producers must match format and material to the intended application. A change that improves one aspect of packaging may affect other characteristics, such as durability, processability, or protection. As a result, product development often involves balancing functional performance with cost, design objectives, and customer expectations.
End-Use Industry Demand
Food and beverage applications form part of the market's broad consumer-goods base. Packaging needs vary according to product type, storage requirements, distribution conditions, and the intended consumer format. Suppliers must provide packaging that suits the product and its route through the supply chain.
Pharmaceutical and healthcare applications have additional requirements linked to product protection and applicable compliance standards. Personal care and cosmetics brands may focus on packaging functionality, appearance, and ease of use. Household care products also require suitable formats based on their contents and handling requirements.
Serving these diverse industries requires packaging companies to maintain capabilities across different materials and product formats. Customer relationships and technical knowledge can be important when adapting packaging designs to a particular application. The breadth of end-use demand also means that market opportunities are shaped by several industries rather than a single consumer category.
EPR Regulations and Recyclable Packaging Innovation
Extended producer responsibility (EPR) regulations are identified as a catalyst for innovation in the Indian flexible packaging market. Regulatory obligations and sustainability considerations can encourage packaging producers and brand owners to review material combinations, packaging design, and end-of-life management. These decisions need to account for both compliance requirements and the functional needs of packaged products.
Mono-material recyclable structures represent a potential opportunity. By reducing the use of incompatible material combinations, suitable mono-material designs may make recycling more practical within systems capable of processing those materials. However, a packaging structure's actual recyclability depends on its composition, design, collection arrangements, and available processing infrastructure. Manufacturers must verify that alternative structures provide adequate protection and can be produced reliably.
The shift toward more recyclable packaging requires collaboration among converters, material suppliers, brands, and recycling stakeholders. Packaging cannot be evaluated on material choice alone: it must continue to perform during filling, storage, distribution, and use. This makes material innovation and production compatibility important considerations for businesses responding to sustainability priorities.
Smart Packaging and Regional Expansion
Smart and active packaging integration is another identified opportunity. Depending on the application, these approaches can add functions beyond basic containment and protection. Their potential use requires assessment of technical suitability, production requirements, costs, and the practical benefit delivered to the product manufacturer or consumer. Adoption may therefore differ between food, healthcare, personal care, and other end-use categories.
Expansion in Tier-2 and Tier-3 cities offers another route for market development. As packaged goods reach consumers across a broader geographic area, manufacturers and brands may need packaging formats suited to changing retail and distribution patterns. This can create demand for different package sizes, material options, and product formats. The extent of growth will depend on consumer preferences, distribution reach, product availability, and the commercial strategies of brands.
Competitive Landscape
Key players identified in the India Flexible Packaging Market include Uflex Ltd., Huhtamaki India, Jindal Poly Films Ltd., Cosmo Films Ltd., EPL Limited, and Amcor plc. Companies compete across factors such as material expertise, manufacturing capabilities, product consistency, design flexibility, and the ability to meet customer specifications. Responsiveness to sustainability requirements and packaging innovation can also influence their market positioning.
For suppliers, the challenge is to accommodate changing packaging expectations while maintaining the technical performance required by different end users. Investments in materials, production processes, and product development must align with customer needs and applicable regulations. Companies also need to consider how packaging solutions will function within existing manufacturing and distribution systems.
India Flexible Packaging Market Forecast
The market is projected to grow at a CAGR of 10.32% during 2026–2035, reaching USD 58.29 billion in 2035 from USD 21.84 billion in 2025. Urbanization, income growth, rural FMCG penetration, EPR-related innovation, and demand from smaller cities are key themes shaping the outlook. Mono-material recyclable structures and smart packaging present additional opportunities for product development. Suppliers that balance functional packaging performance with evolving consumer, commercial, and environmental requirements may be better positioned to serve India's changing packaging market.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
The EMS and ODM Market Analysis reveals a dynamic industry structure with distinct segment dynamics, where EMS holds the largest type share for comprehensive manufacturing solutions, while consumer electronics dominates the application segment as the largest sector for devices like smartphones and wearables. The market analysis shows Asia-Pacific leading the regional market with a 40%...
The Lancet Market is an important segment of the medical device industry, supported by the increasing need for convenient and reliable blood sampling solutions. Lancets are commonly used for capillary blood collection in glucose monitoring and other diagnostic procedures. Their ease of use, portability, and relatively simple design make them valuable across hospitals, diagnostic centers,...
The Common Drugs Use In Ophthalmology Market has experienced substantial growth in recent years, driven by increasing prevalence of eye diseases and expanding therapeutic options across all age groups. These pharmaceutical agents address conditions ranging from dry eye syndrome and glaucoma to age-related macular degeneration and diabetic retinopathy. Ophthalmologists and optometrists...
The Coagulation Poc Analyzer Market has experienced significant growth in recent years, driven by increasing demand for rapid, near-patient coagulation testing in anticoagulation clinics, emergency departments, operating rooms, and outpatient settings. These portable diagnostic instruments measure key hemostasis parameters including prothrombin time, international normalized ratio, activated...
The increasing demand for non-invasive diagnostic imaging, rising prevalence of cardiovascular and oncological disorders, and growing adoption of contrast-enhanced ultrasound (CEUS) are driving the growth of the microbubbles ultrasound contrast agents market. However, the market also faces several challenges. Stringent regulatory approval requirements, high development costs, and...