

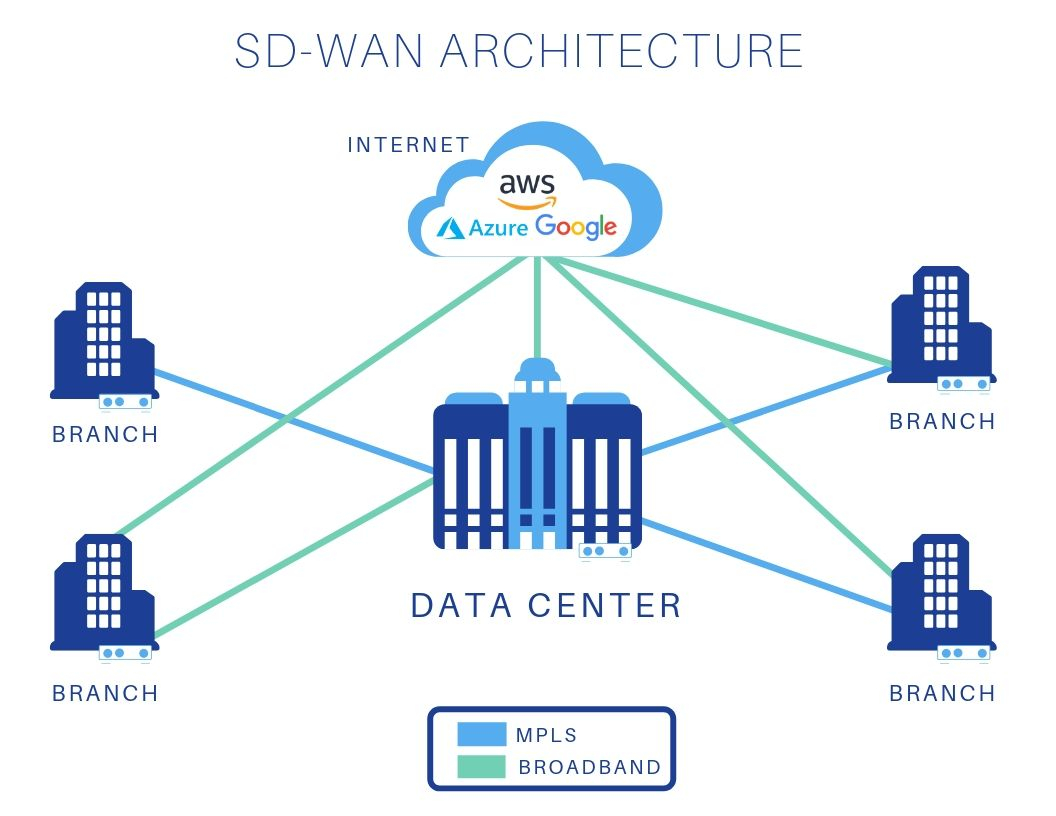
Analyzing Competitive Dynamics in the Software Defined Wide Area Network Market Share
Dominant Players and Market Consolidation
The competitive landscape of modern virtualized networking is characterized by intense rivalry among established telecommunications giants and agile technology specialists. Analyzing the Software Defined Wide Area Network Market Share reveals a polarized environment where a few multinational technology conglomerates control massive enterprise client bases, while software-driven providers dominate cloud optimization verticals. Strategic mergers and acquisitions frequently reshape this hierarchy, as major telecom operators absorb nimble networking startups to acquire proprietary orchestration software, AI automation models, or specialized security protocols. This consolidation trend challenges independent providers to differentiate themselves through superior service level agreements, uncompromising cybersecurity standards, or deep industry-specific protocol integrations. Enterprise buyers must carefully evaluate vendor stability, roadmap transparency, and ecosystem lock-in risks when selecting long-term communication partners to ensure operational continuity.
Strategies for Differentiated Positioning
To capture and retain meaningful market segments, emerging service providers must cultivate unique value propositions beyond basic router monitoring and plug-and-play connectivity functionality. Differentiation often manifests through advanced closed-loop network automation, specialized compliance certifications, or superior cross-platform compatibility with legacy enterprise branch hardware. Some providers focus on air-gapped, high-security architectures, appealing directly to defense contractors and critical infrastructure operators handling sensitive communications. Others prioritize real-time collaborative network dashboards that rival dedicated enterprise asset management suites, reducing the need for multiple disparate software subscriptions. By identifying underserved market niches—such as maritime satellite connectivity management or remote mining communication tracking—independent vendors can carve out profitable domains shielded from direct competition with broad-spectrum tech monopolies.
Customer Retention and Ecosystem Lock-In
Maintaining high customer retention rates is essential for sustaining market share within the fiercely competitive virtualized networking sector. Providers frequently employ ecosystem lock-in strategies, embedding their management platforms deeply into daily enterprise workflows, third-party ticketing systems, and IT administrator habits. When corporate teams rely on specialized custom dashboards, automated provisioning scripts, and integrated notification tools tied to a specific provider platform, switching costs become prohibitively high. Consequently, vendors invest heavily in customer success initiatives, responsive 24/7 technical support, and continuous service upgrades to keep user satisfaction high and churn rates minimal. However, growing regulatory scrutiny regarding data portability and open standards may encourage more fluid multi-vendor strategies, prompting vendors to compete increasingly on service reliability rather than artificial barriers.
Strategic Partnerships and Channel Alliances
Collaboration between software vendors, telecommunication carriers, and system integrators plays a pivotal role in expanding market footprint and driving enterprise acquisition. Channel partners act as trusted advisors, bundling virtualized networking services, secure cloud gateways, and analytics software into comprehensive digital transformation packages for medium and large enterprises. Telecommunications companies frequently bundle managed connectivity with high-speed private cloud plans, capturing vast commercial markets efficiently. Strategic alliances also facilitate seamless interoperability between competing carrier environments, enhancing overall user convenience and accelerating industry-wide standardization efforts like MEF standards. These collaborative networks amplify marketing reach and enable smaller service providers to penetrate international markets that would otherwise require prohibitive localized sales operations.
Navigating Antitrust and Regulatory Pressures
The immense concentration of communication data and network routing infrastructure among a handful of dominant technology providers has attracted intense regulatory scrutiny worldwide. Antitrust authorities increasingly investigate monopolistic practices, data hoarding, and unfair bundling strategies within the networking sector. Companies holding significant market share must navigate complex compliance landscapes, ensuring open application programming interfaces and fair data portability for departing corporate clients. These regulatory interventions aim to foster a healthier, more competitive ecosystem where innovative startups can emerge without facing insurmountable barriers erected by legacy tech titans. Strategic leaders must remain adaptable, proactively aligning their corporate governance and service architectures with evolving legal expectations to mitigate compliance risks and sustain long-term enterprise trust.
➤ Latest Market Intelligence from Market Research Future:

