A Detailed Breakdown of the Various Virtualized Evolved Packet Core Market Types

Segmentation by Component: The Solutions and Services Ecosystem
A fundamental way to classify the Virtualized Evolved Packet Core Market Types is by its core components, which are broadly categorized into solutions and services. The solutions segment forms the technological heart of the market. This includes the vEPC software itself, which comprises the various Virtual Network Functions (VNFs) or Cloud-native Network Functions (CNFs) that make up the mobile core. These are the virtualized versions of the Mobility Management Entity (vMME), Serving Gateway (vSGW), Packet Data Network Gateway (vPGW), and Home Subscriber Server (vHSS). This segment also crucially includes the Management and Network Orchestration (MANO) software, which is the "brain" responsible for automating the deployment, scaling, and lifecycle management of these network functions. The services segment is equally critical and is rapidly growing. This encompasses a wide range of professional services, including consulting to help operators plan their virtualization strategy, complex systems integration to deploy the vEPC solution and integrate it with legacy systems (like billing and OSS), and training services. It also includes managed services, where a third party takes on the responsibility for operating and maintaining the vEPC on behalf of the operator, an increasingly popular option for enterprises and smaller service providers.
Categorization by Deployment Model: Private, Public, and Hybrid Cloud
The choice of deployment model is another critical market segmentation, reflecting the diverse operational and strategic needs of different operators. The on-premises private cloud model was the initial and most common deployment type. In this model, the operator builds and manages their own NFV Infrastructure (NFVI)—a cloud environment built on COTS servers—within their own data centers. This approach offers the highest level of control, security, and performance predictability, and it is often favored by large, established mobile operators with existing data center assets and strict data sovereignty requirements. The public cloud deployment model is a newer and rapidly growing type. Here, the vEPC software is deployed on the infrastructure of a major public cloud provider like Amazon Web Services (AWS), Microsoft Azure, or Google Cloud. This model offers tremendous advantages in terms of scalability, agility, and a pay-as-you-go cost structure, eliminating the need for upfront hardware investment. It is particularly attractive for greenfield operators, MVNOs, and for specific use cases like disaster recovery. The hybrid cloud model combines both approaches, allowing operators to run certain sensitive or latency-critical functions in their private cloud while leveraging the public cloud for less critical functions or for bursting capacity during peak demand, offering a "best of both worlds" approach.
Segmentation by Use Case: MNO, MVNO, and Enterprise Private Networks
The market can also be segmented by the primary use case or the type of organization deploying the vEPC. The largest segment by far is for public Mobile Network Operators (MNOs). These are the large, national carriers like AT&T, Vodafone, or Telefónica, who are deploying vEPC to modernize their nationwide 4G and 5G networks, manage massive subscriber bases, and handle enormous volumes of data traffic. Their requirements are focused on carrier-grade reliability, massive scalability, and seamless interoperability with their existing, complex infrastructure. A smaller but important segment is the Mobile Virtual Network Operator (MVNO). MVNOs typically lease network access from MNOs. By deploying their own lightweight vEPC, they can gain more independence and control over their service offerings, subscriber management, and branding, allowing them to create more differentiated and profitable services. The most dynamic and fastest-growing use case is the Enterprise/Private Network segment. Large enterprises in manufacturing, logistics, mining, and other industries are deploying their own private LTE and 5G networks to support their digital transformation and Industry 4.0 initiatives. A dedicated, on-premises or cloud-hosted vEPC provides them with the secure, reliable, and high-performance core network needed to run their mission-critical applications, representing a massive new growth vector for the market.
Functional Market Types: The Core Virtual Network Functions (VNFs)
Delving into the solution itself, the market can be segmented by the individual virtual network functions (VNFs) that are being deployed. While a full vEPC solution includes a suite of functions, operators often deploy them in phases or source them from different vendors, creating a market for individual components. The vMME (virtualized Mobility Management Entity) is a critical control-plane function, and its market is driven by the need to handle the signaling load from billions of IoT devices and smartphones. The vSGW (virtualized Serving Gateway) and vPGW (virtualized Packet Data Network Gateway) are often discussed together as the virtualized gateways. Their market is driven directly by the growth in data traffic, as they are responsible for forwarding all user data. The implementation of Control and User Plane Separation (CUPS) has further segmented this market into control-plane (SGW-C, PGW-C) and user-plane (SGW-U, PGW-U or UPF) functions. The vHSS (virtualized Home Subscriber Server), or its 5G equivalent, the UDM/UDR, represents the market for the virtualized subscriber database. Finally, the vPCRF (virtualized Policy and Charging Rules Function) is the market for the virtualized policy engine, which is critical for implementing tiered data plans, quality of service, and other business rules. This functional segmentation highlights the modular nature of the vEPC architecture and the multi-faceted market it has created.
Top Trending Reports:
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
Examining the security safes market, covering advanced protection technologies for commercial and industrial applications, key product types including fireproof and burglary safes, and the future outlook for commercial security safes through 2035. The Security Safes Market represents the comprehensive landscape of advanced protection technologies, providing essential secure storage solutions...
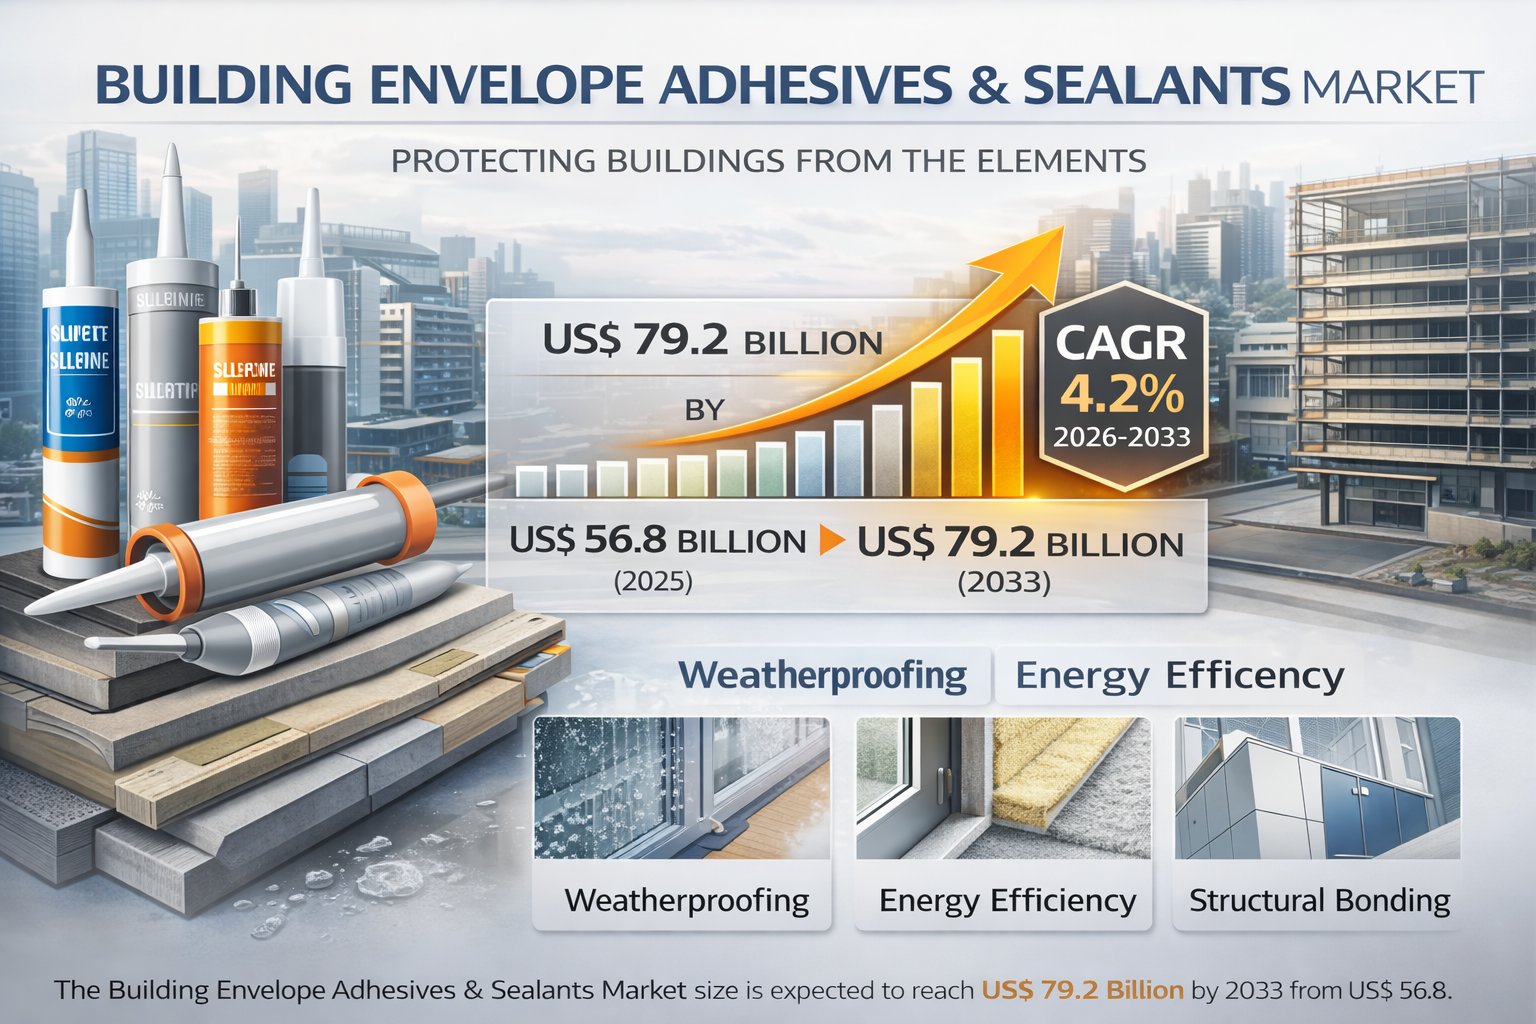
The global construction industry is undergoing a radical transformation, driven by the dual needs of structural durability and superior energy efficiency. At the heart of this shift is the building envelope the physical separator between the conditioned and unconditioned environment of a building. The growing emphasis on airtightness and thermal performance has catapulted the demand for...
Slip Ring market is gaining momentum with the expansion of robotics and automated production lines across various industries. Slip rings enable continuous rotation while maintaining uninterrupted electrical connectivity in robotic arms and industrial machinery. Rising adoption of Industry 4.0 solutions is supporting sustained market demand. The Slip Ring market was valued...
The devices carried by frontline police officers, paramedics, and firefighters across the United Kingdom are changing rapidly to match modern digital standards. For decades, emergency workers carried bulky, single-purpose handheld radios that could only transmit voice messages over narrow radio channels. If an officer needed to access a national vehicle database or view a missing person...
Custom Cookies Mylar Bags keep cookies fresh and safe while giving a clean, simple look that works for small brands and home baking setups. When you pack cookies the right way, it changes everything. It is not just about keeping them safe but also about how they look and feel when someone holds them. Custom Cookies Mylar Bags have slowly become a go-to choice for people who bake at home or run...