


Breaking: High Density Interconnect PCB Market Set for Exponential Growth by 2035

The High Density Interconnect PCB market is on the verge of a significant transformation, driven by robust technological advancements and increasing demand across various sectors. With projections indicating a market size of approximately USD 35,205.74 million by 2035, the industry is witnessing a remarkable compound annual growth rate (CAGR) of 17.28%. This trajectory underscores a pivotal shift toward miniaturization and efficiency in electronic components, positioning key players to capitalize on emerging opportunities. As industries evolve, the demand for high-performance circuit boards that meet stringent specifications has never been higher. The convergence of technology and consumer needs is laying a foundation for unprecedented growth.
Current market dynamics highlight the competitive landscape, where major players are crucial to the sector's evolution. Industry leaders such as Avery Dennison (US), AT&S (AT), and Jabil (US) are making significant strides in innovation, pushing the boundaries of what is possible in PCB design and functionality. Additionally, Nippon Mektron (JP) and Unimicron Technology (TW) are focused on developing advanced materials that enhance the performance of high-density interconnects. This competitive landscape is further enriched by companies like Zhen Ding Technology Holding Limited (TW) and Shenzhen Fastprint Circuit Tech (CN), which are expanding their offerings to meet the growing demand for sophisticated electronic solutions. Samsung Electro-Mechanics (KR) and Flex Ltd. (SG) also play pivotal roles, providing essential components that cater to various sectors, including automotive, telecommunications, and consumer electronics. The development of market analysis continues to influence strategic direction within the sector.
Several key drivers are propelling the high-density interconnect PCB market forward. The surge in demand for consumer electronics is a primary catalyst, as manufacturers seek to produce smaller, more efficient devices that do not compromise on functionality. Concurrently, advancements in telecommunications and the proliferation of 5G technology are reshaping the landscape, necessitating high-performance PCBs that can handle increased data transmissions. Another influential factor is the ongoing trend toward sustainability. Companies are increasingly adopting eco-friendly manufacturing practices, prompting innovations in materials and design. However, challenges remain, such as rising material costs and the complexity of manufacturing processes, which can impact profitability. Despite these hurdles, the focus on R&D is expected to drive further breakthroughs, enabling firms to navigate these challenges effectively.
Regionally, the market dynamics vary, with North America leading in terms of innovation and market size. The North American market is characterized by a strong preference for advanced materials and high-performance applications, driven largely by the telecommunications and automotive industries. For instance, the automotive sector is expected to account for approximately 30% of the total PCB market by 2025, underlining the critical role of PCBs in electric and autonomous vehicles. The Asia-Pacific region, particularly countries like China and Japan, is witnessing rapid growth, fueled by increasing consumer electronics manufacturing and adoption of advanced technologies. In fact, the Asia-Pacific market is projected to grow at a CAGR of 19.5%, significantly outpacing North America. The competitive landscape in these regions is diverse, with local players competing alongside international giants, creating a vibrant ecosystem for growth. Comparative analysis indicates that while North America currently dominates, the Asia-Pacific region's growth potential is significant, providing ample investment opportunities.
Investment opportunities within the High Density Interconnect PCB Market are becoming increasingly visible, particularly in the realms of technology enhancement and sustainability initiatives. Companies are actively exploring partnerships and collaborations to leverage cutting-edge technologies that can improve efficiency and product performance. The rising focus on miniaturization presents unique avenues for innovation, as organizations strive to design PCBs that meet evolving consumer demands. Furthermore, the shift toward more sustainable practices is encouraging investment in green technologies, which not only enhance the environmental footprint but also resonate with a growing base of environmentally conscious consumers. As market dynamics evolve, stakeholders must continuously assess their strategies to align with these emerging trends and capitalize on the lucrative prospects available.
The future outlook for the High Density Interconnect PCB market is promising, with significant growth projected through 2035. Expert perspectives suggest that ongoing technological advancements, coupled with increased investments in R&D, will further enhance the market's trajectory. As industries continue to integrate high-density interconnect technologies into their operations, a ripple effect will likely take place, influencing various sectors and creating new applications. Companies that proactively adapt to these changes will be best positioned to capture market share, driving innovation and contributing to the sector's overall expansion. Additionally, considering the growing emphasis on IoT devices, which are projected to reach 75 billion units by 2025, the demand for high-density interconnect PCBs will likely accelerate, further solidifying the market's upward momentum.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
The Veterinary/Animal Vaccines Market is expanding as animal health becomes an increasingly important priority for pet owners, livestock producers, veterinarians, and agricultural businesses. Veterinary vaccines help prevent infectious diseases across companion animals, livestock, poultry, swine, and aquaculture populations. Market Research Future reports that the market was valued at...

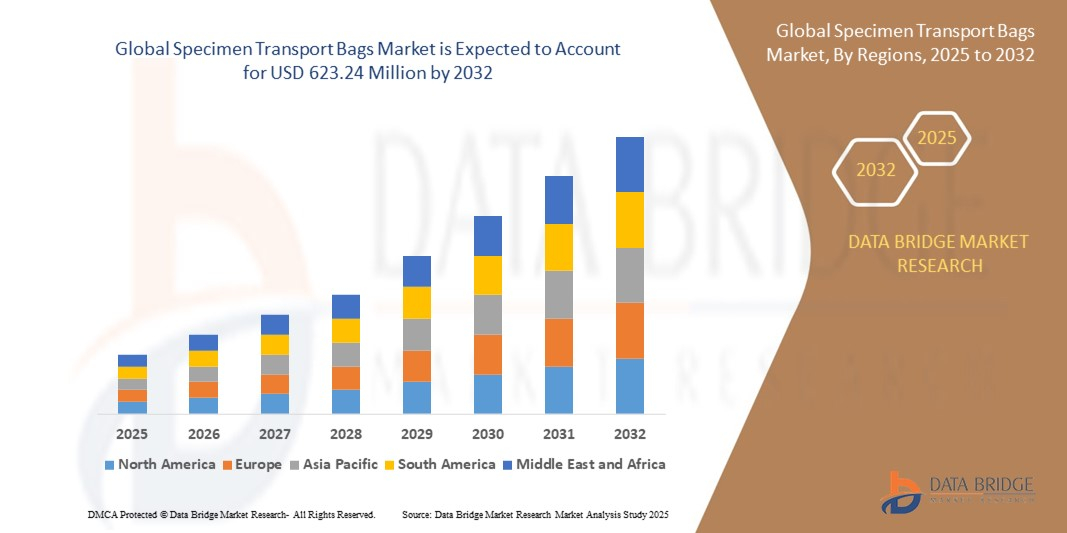
According to the latest report published by Data Bridge Market Research, the Specimen Transport Bags Market CAGR Value The global specimen transport bags market size was valued at USD 295.01 million in 2024 and is expected to reach USD 623.24 million by 2032, at a CAGR of 9.8% during the forecast period This Specimen Transport Bags Market research report is prepared...
Substance Abuse Treatment Market is expanding as healthcare systems place greater emphasis on prevention, treatment, rehabilitation, and long-term recovery for people affected by substance use disorders. Treatment programs increasingly combine medical care, behavioral therapies, counseling, and social support according to individual patient needs. Treatment approaches can include...
The PCR Master Mixes Market is expanding as polymerase chain reaction technologies become increasingly important in molecular diagnostics, biotechnology, pharmaceutical research, genomics, and forensic science. PCR master mixes are pre-formulated reagent solutions containing essential components such as DNA polymerase, nucleotides, buffers, and stabilizing agents, helping laboratories...
The Surgical Equipment Market is experiencing significant transformation as healthcare providers increasingly adopt advanced technologies and minimally invasive surgical techniques. According to Market Research Future, the market stood at USD 18.55 billion in 2025 and is projected to reach USD 38.25 billion by 2035, registering a CAGR of 7.50% during the forecast period. The increasing...
