Travel Credit Insurance Market: The Role of Digital Transformation and Embedded Protection
The Travel Credit Insurance Market is evolving as digital technology changes the way consumers plan journeys, purchase travel services, and manage financial risks. Travelers increasingly rely on online platforms to compare flights, reserve accommodations, arrange transportation, and organize complete holiday experiences. These digital transactions create opportunities for insurers to offer relevant protection when customers are already considering the financial consequences of a trip. Through embedded insurance, eligible coverage options can be presented within booking platforms, banking applications, or payment services, making protection easier to discover and purchase.
Embedded insurance is particularly valuable because it reduces the separation between buying a travel service and considering the associated risks. Traditionally, customers might have needed to research an insurance provider independently after making travel arrangements. Integrated systems can present coverage information during checkout, allowing consumers to review available benefits before confirming a purchase. Depending on the arrangement, the protection may be provided by an insurer and distributed through a travel company, financial institution, or digital intermediary. This model can improve convenience while creating additional distribution opportunities for insurance businesses.
Mobile technology is also influencing policy administration. Customers increasingly expect to access policy documents, coverage summaries, emergency contact details, and claims instructions through their smartphones. Mobile applications can provide reminders about documentation requirements, notifications regarding claim status, and access to customer support. These features can reduce confusion and help travelers manage their protection while away from home. For insurers, digital self-service options can reduce repetitive administrative work and enable service teams to focus on more complex cases.
Artificial intelligence and data analytics may further improve insurance operations. Automated systems can help classify claims, identify missing documents, detect unusual transaction patterns, and direct inquiries to the appropriate service channel. Predictive analytics can support underwriting by helping insurers evaluate risk factors and understand changing travel patterns. However, these technologies must be implemented with suitable safeguards. Inaccurate data, biased models, or excessive automation can lead to unfair decisions and frustrating customer experiences. Human review, data protection, and clear explanations remain important components of responsible digital insurance services.
Another opportunity lies in simplifying the claims process. Travelers experiencing cancellations or interruptions may already be dealing with stressful circumstances, making complicated paperwork particularly difficult. Digital claim submission can allow customers to upload receipts, booking confirmations, cancellation notices, and other supporting documents without visiting an office. Where appropriate and legally permitted, insurers may also use verified transaction information to reduce the need for customers to provide documents repeatedly. Faster processing depends on the quality of the evidence, policy conditions, and complexity of the claim, so digitalization should not be presented as a guarantee of automatic reimbursement.
Partnerships between banks, card issuers, travel agencies, and insurers can support broader distribution. Financial institutions may use insurance benefits to differentiate their credit cards, while travel platforms can offer protection alongside bookings. Insurers gain access to customers who may not otherwise investigate standalone products. Nevertheless, the distribution arrangement must clearly identify the insurer, explain the scope of cover, and disclose any eligibility requirements. Customers should understand whether they are receiving an included benefit, purchasing optional insurance, or accessing a separate service.
Cybersecurity and privacy are critical considerations in this digital environment. Insurance transactions may involve personal identification, payment information, travel itineraries, medical documentation, and financial records. Organizations must protect this information through appropriate security controls, restricted access, secure storage, and responsible data-sharing arrangements. Any use of customer data for automated decisions should follow applicable legal requirements and organizational policies. A strong approach to privacy can support trust and reduce the operational and reputational consequences of data incidents.
The market also faces challenges associated with uneven digital access. Some consumers prefer face-to-face assistance or require policy information in languages that are not widely supported by digital platforms. Others may have limited familiarity with online insurance purchases. Providers can address these barriers through accessible website design, multilingual documentation, telephone support, and partnerships with established travel intermediaries.
In the coming years, digital transformation is likely to remain a major competitive factor in the Travel Credit Insurance Market. The strongest opportunities will come from combining convenient purchasing with clear explanations, reliable claims handling, and relevant coverage. Technology can improve the insurance experience, but it cannot replace the need for sound underwriting, transparent terms, and responsible customer service.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
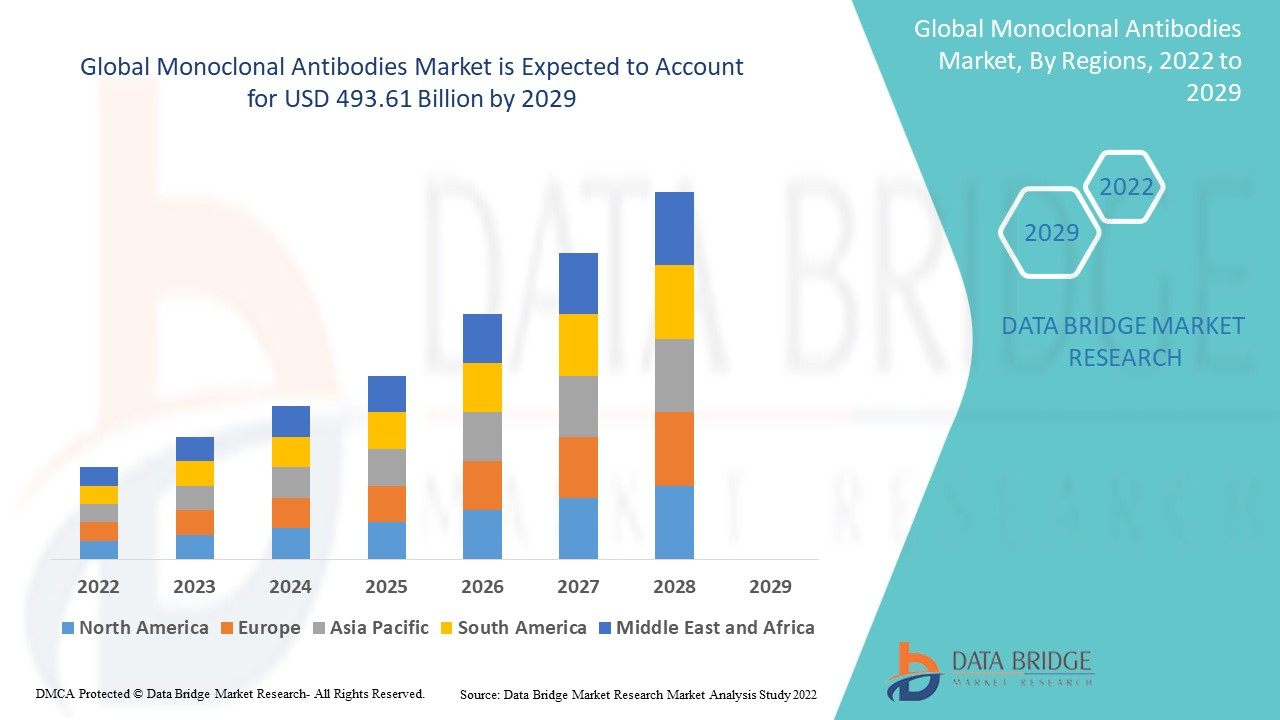
" According to the latest report published by Data Bridge Market Research, the Monoclonal Antibodies Market CAGR Value Global monoclonal antibodies market size was valued at USD 263.22 billion in 2024 and is projected to reach USD 719.81 billion by 2032, with a CAGR of 13.40% during the forecast period of 2025 to 2032. A team involved in preparing this Monoclonal Antibodies...
The global packaging industry is witnessing a significant transformation, driven by the increasing demand for product safety, extended shelf life, and consumer convenience. Among various packaging modalities, blister packaging has emerged as a cornerstone, particularly within the pharmaceutical and consumer goods sectors. This packaging method involves the use of pre formed plastic or foil...

The Medical Engineered Materials industry plays a significant role in supporting the development of next-generation healthcare products and technologies. These advanced materials are widely used in medical devices, implants, prosthetics, surgical equipment, and diagnostic applications, offering improved functionality and performance. The increasing focus on innovation in healthcare and the...
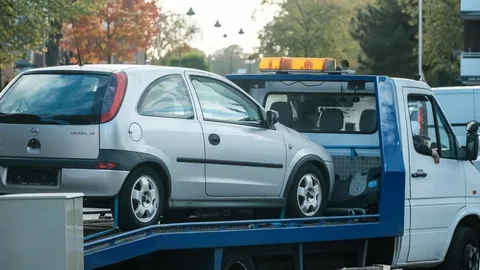
Sie fahren nach einem langen Tag nach Hause. Die Straßen sind nass vom vorherigen Regen. Sie nehmen eine Kurve etwas zu schnell. Plötzlich taucht ein anderes Auto aus dem Nichts auf. Es gibt einen lauten Knall. Ihr Airbag löst aus. Für einen Moment wird alles still. Sie sind geschockt aber in Ordnung. Ihr Auto hingegen ist es nicht. Diese Szene spielt sich jeden Tag auf den...
The Air Quality Control Systems Market was valued at US$ 114.24 Billion in 2025 and is projected to reach US$ 191.93 Billion by 2033, registering a CAGR of 6.70% during 2026–2033. The outlook combines expanding addressable demand with a need for disciplined execution across products, regions and channels. This version applies a balanced market structure and execution priorities lens while...