

Semiconductor Packaging Substrates Market Research Report: Key Players and Competitive Landscape
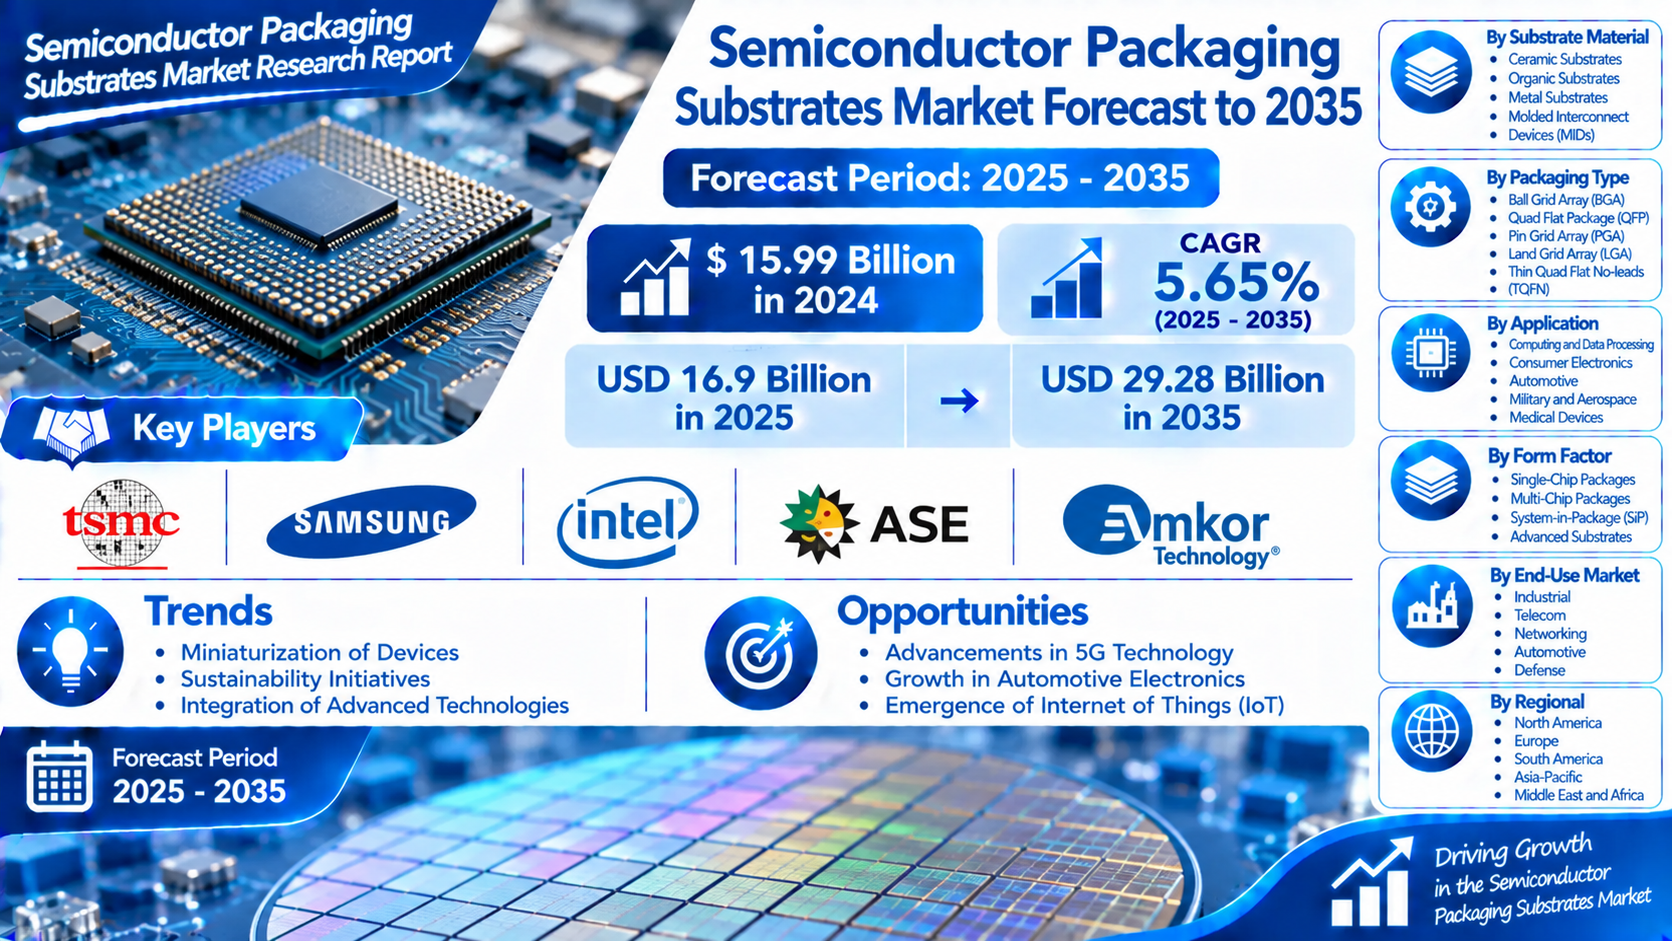
According to Market Research Future® (MRFR), the Semiconductor Packaging Substrates Market is expected to record a CAGR of 5.65% over the 2025–2035 forecast period, with its value projected to rise from USD 16.9 billion in 2025 to USD 29.28 billion by 2035. The market was valued at USD 15.99 billion in 2024. Its development is linked to the evolving requirements of computing and data processing, consumer electronics, automotive, military and aerospace, and medical devices. Miniaturization, advanced technology integration, and opportunities associated with 5G and the Internet of Things (IoT) are important themes in the industry's outlook.
Semiconductor Packaging Substrates: Market Context
Packaging substrates are an important part of the semiconductor packaging ecosystem. The market's segmentation reflects the range of materials and packaging formats used to address different electronic product requirements. It also covers multiple application and end-use markets, indicating the broad industrial reach of semiconductor packaging substrates.
The market is forecast to increase from USD 15.99 billion in 2024 to USD 16.9 billion in 2025, before reaching USD 29.28 billion by 2035. This represents a CAGR of 5.65% during 2025–2035. The projected expansion is associated with demand across electronic and specialized applications, including computing, consumer devices, automotive systems, military and aerospace equipment, and medical devices.
The industry is also influenced by three identified trends: miniaturization of devices, sustainability initiatives, and integration of advanced technologies. These themes reflect changing priorities in semiconductor packaging and the need to consider substrate solutions alongside evolving device designs and technology requirements.
Substrate Materials and Packaging Configurations
Four substrate material categories are included in the market: ceramic substrates, organic substrates, metal substrates, and molded interconnect devices (MIDs). This segmentation demonstrates the variety of material options represented in semiconductor packaging. Different packaging applications may require different substrate characteristics, making material selection an important consideration for manufacturers and buyers.
Packaging type provides a separate classification. Ball Grid Array (BGA), Quad Flat Package (QFP), Pin Grid Array (PGA), Land Grid Array (LGA), and Thin Quad Flat No-leads (TQFN) are the five identified categories. These formats represent different packaging configurations available within the market.
The presence of multiple substrate materials and packaging types gives the industry a broad product structure. Manufacturers must consider the relationship between the substrate and packaging format when serving customers across different applications. As device designs continue to change, packaging requirements remain a relevant part of semiconductor product development.
Miniaturization and Advanced Packaging Formats
Miniaturization of devices is one of the market's key trends. The development of electronic products places continuing attention on device size and the packaging formats used to accommodate semiconductor components. This trend makes substrate and package design important considerations across the industry.
The market's form factor segmentation includes single-chip packages, multi-chip packages, system-in-package (SiP), and advanced substrates. These categories represent the different form factors covered by the market. Their inclusion highlights the range of packaging solutions associated with the industry's customer requirements.
Integration of advanced technologies is another identified trend. As technology requirements evolve, packaging solutions must remain aligned with the needs of the applications they serve. Advanced substrates and system-in-package formats are included in the market's segmentation, providing further context for the industry's focus on packaging development.
Applications and End-Use Markets
The market serves five application categories: computing and data processing, consumer electronics, automotive, military and aerospace, and medical devices. Computing and data processing and consumer electronics reflect the industry's connection with electronic products and systems. Automotive applications provide another important category, particularly as growth in automotive electronics is identified as a market opportunity.
Military and aerospace applications extend the market into specialized areas, while medical devices add another distinct application group. These sectors contribute to a broad demand structure and require suppliers to address different packaging needs.
The end-use market segmentation includes industrial, telecom, networking, automotive, and defense. Telecom and networking are particularly relevant to the opportunity associated with advancements in 5G technology. Automotive appears in both the application and end-use classifications, reinforcing its position in the market structure. The industrial and defense categories further broaden the range of markets served.
5G and Internet of Things Opportunities
Advancements in 5G technology are identified as an opportunity for the semiconductor packaging substrates market. The development of 5G expands the technology landscape in which semiconductor components are used, connecting packaging requirements with the telecom and networking end-use categories.
The emergence of the Internet of Things (IoT) is another identified opportunity. IoT represents an expanding area of connected-device development and adds to the range of applications associated with semiconductor components. As connected technologies evolve, packaging substrates remain part of the wider ecosystem supporting electronic devices.
Growth in automotive electronics provides a third opportunity. The automotive application and end-use categories demonstrate the sector's importance to the market. These opportunities complement the broader trend of advanced technology integration and the industry's focus on accommodating changing device requirements.
Regional Scope and Leading Companies
The market covers North America, Europe, South America, Asia-Pacific, and the Middle East and Africa. These regions form the geographic framework for the industry's assessment and reflect the international scope of semiconductor packaging substrate demand.
The key companies identified include Taiwan Semiconductor Manufacturing Company, Samsung Electronics, Intel Corporation, ASE Technology Holding Co., Ltd., and Amkor Technology. These businesses are part of the competitive landscape. Market participants operate across a sector where substrate materials, packaging formats, and application requirements are important dimensions of product development and positioning.
Competition is connected with the ability to address changing requirements across electronic and specialized markets. Miniaturization, sustainability initiatives, and advanced technology integration provide important context for the industry's development.
Market Outlook to 2035
The semiconductor packaging substrates market is projected to reach USD 29.28 billion by 2035, increasing from USD 16.9 billion in 2025 at a CAGR of 5.65%. Its market structure spans several substrate materials, packaging types, form factors, applications, and end-use markets.
Opportunities associated with 5G technology, automotive electronics, and IoT provide additional areas of potential development. Alongside these opportunities, device miniaturization and advanced technology integration are expected to remain relevant industry themes. The market's broad application base and evolving packaging requirements provide the foundation for its projected expansion through 2035.

