


What Does Home Insurance Actually Cover? A Complete Guide

Home insurance serves as a critical financial safeguard for homeowners, protecting against unexpected damages and liabilities. In an era of rising natural disasters, theft, and everyday accidents, understanding your policy details can mean the difference between financial stability and devastating loss. Home insurance Qatar provides tailored options that align with local regulations and environmental risks unique to the region, helping residents navigate coverage in a dynamic housing market. This guide explores every aspect of home insurance to empower you with knowledge for informed decisions.
The foundation of any home insurance policy begins with its core purpose: transferring risk from the homeowner to the insurer. Policies typically combine multiple coverages into one package, often called a homeowners insurance policy. These include protection for the physical structure, personal belongings, and legal responsibilities. While specifics vary by provider and location, standard policies follow similar frameworks worldwide. Early comprehension of these elements prevents surprises during claims.
Beyond basic protection, modern home insurance adapts to lifestyle needs. Additional riders or endorsements can cover high-value items, flood risks, or even temporary living expenses after a covered event. Homeowners should review their policies annually, as life changes like renovations or new valuables can affect coverage adequacy. This proactive approach ensures your insurance evolves with your home.
Understanding exclusions is equally important. Many assume comprehensive protection, yet certain perils like earthquakes or gradual wear require separate policies. By familiarizing yourself with both inclusions and exclusions, you avoid gaps that could lead to out-of-pocket expenses. Consulting independent agents helps customize plans effectively.
Types of Home Insurance Policies
Several policy forms exist, each suited to different needs. The most common is the HO-3 (special form), which offers open perils coverage for the dwelling—protecting against all risks except listed exclusions—and named perils for personal property. HO-5 policies provide broader open perils coverage for both structure and contents, ideal for newer or high-value homes.
HO-4 policies, known as renters insurance, focus on personal property and liability without dwelling coverage. HO-6 targets condo owners, covering the interior while the master policy handles the building exterior. HO-8 suits older homes where replacement costs exceed market value, using actual cash value instead of replacement cost.
Each type balances premiums against protection levels. Factors like construction materials, location, and security features influence availability and pricing. In coastal or wildfire-prone areas, insurers may impose higher deductibles or require mitigation measures for approval.
Core Coverages Explained
Dwelling coverage forms the policy backbone, reimbursing repairs or rebuilding of the home's structure—including walls, roof, floors, and built-in appliances—after covered events like fire, windstorms, or hail. It typically extends to attached structures such as garages and decks. Importantly, this coverage aims for replacement cost, paying to restore the home to its pre-loss condition without depreciation.
Other structures coverage protects detached elements like fences, sheds, or pools, usually at 10% of dwelling limits. This proves valuable when storms damage landscaping features or outbuildings.
Personal property coverage safeguards belongings inside the home and sometimes off-premises at a percentage of dwelling limits (often 50-70%). It includes furniture, clothing, electronics, and jewelry, subject to sub-limits for valuables. Actual cash value policies deduct depreciation, while replacement cost options restore items at current prices—worth the slight premium increase for most households.
Loss of use or additional living expenses (ALE) covers hotel stays, restaurant meals, and other costs while your home undergoes repairs. Policies usually cap this at 20-30% of dwelling coverage with time limits, providing crucial support during displacement.
Liability protection addresses legal and medical costs if someone injures themselves on your property or if your actions damage others' belongings. Standard limits start at $100,000 but experts recommend $300,000 or more. This coverage extends to family members and even pets in many cases. Umbrella policies offer excess liability beyond standard limits for broader protection.
Medical payments coverage handles minor injuries to guests regardless of fault, typically up to $1,000-$5,000 per person, facilitating quick resolutions without lawsuits.
What Home Insurance Typically Does Not Cover
Standard policies exclude flood and earthquake damage, necessitating separate policies through the National Flood Insurance Program (NFIP) or private carriers. Earthquakes often require riders in high-risk zones. Mold, termites, and gradual deterioration also fall outside coverage, emphasizing maintenance responsibilities.
Wear and tear, neglect, or intentional damage void claims entirely. War, nuclear hazards, and government actions remain excluded. High-value items like art or collectibles often need scheduled personal property endorsements with appraisals.
In regions with specific risks, such as hurricanes, windstorm deductibles may apply separately and reach 2-5% of dwelling coverage. Understanding these limitations allows homeowners to layer protections effectively.
Factors Influencing Premiums and Coverage
Multiple variables determine costs. Home value, construction type, location, claims history, and credit score all play roles. Homes with modern safety features—smoke detectors, security systems, storm shutters—often qualify for discounts. Bundling with auto insurance can yield 10-25% savings.
Deductibles represent the amount you pay before insurance activates. Higher deductibles lower premiums but increase out-of-pocket costs during claims. Inflation guard endorsements automatically adjust dwelling limits annually to combat rising rebuild costs.
Insurers assess risk through inspections or satellite imagery, sometimes requiring updates for older electrical or plumbing systems. In areas prone to climate events, availability shrinks, pushing homeowners toward state-backed insurers or surplus lines.
The Claims Process Step by Step
Successful claims begin with immediate documentation. Contact your insurer promptly, take photos, and secure the property to prevent further damage. Provide police reports for theft or vandalism. Maintain records of temporary expenses for ALE reimbursement.
Adjusters inspect damages and estimate repairs. Independent appraisals help if disagreements arise. Insurers issue payments in stages: initial for emergency repairs, then further installments upon completion. Full documentation, including receipts, accelerates settlements.
Common pitfalls include under-insuring (triggering coinsurance penalties) or delaying notifications. Policyholders should understand "proof of loss" requirements and timelines, typically 30-60 days for detailed inventories.
Special Considerations for High-Value Homes and Unique Properties
Luxury homes or historic properties may require specialized policies with agreed value or guaranteed replacement cost. These ensure full rebuilding regardless of policy limits. Vacation homes often need separate seasonal policies addressing vacancy risks.
Green home features like solar panels or energy-efficient systems might qualify for eco-friendly discounts while requiring specific endorsements. Home-based businesses need commercial riders, as standard policies exclude business property and liability.
International and Regional Variations
Coverage nuances differ globally based on local laws and risks. In some markets, mandatory elements address seismic activity or extreme weather. Policy language and claim resolution speeds vary, making professional advice essential when relocating.
Tips for Choosing the Right Policy
- Assess true replacement cost using calculators or professional appraisers rather than market value.
- Compare multiple quotes through independent brokers for unbiased options.
- Read the declarations page and full policy wording carefully.
- Evaluate insurer financial strength via ratings from AM Best or Moody's.
- Consider future needs—growing families or planned improvements.
- Review annual renewals for creeping premium increases or coverage reductions.
Maintain an up-to-date home inventory using apps or cloud storage. Video walkthroughs with timestamps provide powerful evidence during claims.
Common Myths Debunked
Many believe landlord insurance equals homeowners coverage—it doesn't. Landlords need separate policies addressing rental-specific risks. Others assume all water damage is covered, yet gradual leaks from poor maintenance are typically excluded while sudden pipe bursts qualify.
"Act of God" doesn't remove all responsibilities; covered perils still apply within policy terms. Comprehensive doesn't mean all-inclusive—it's a specific term for auto insurance.
Future Trends in Home Insurance
Climate change drives innovation. Insurers increasingly use AI for risk assessment and parametric policies paying fixed amounts upon trigger events like earthquake magnitude. Smart home integrations offer real-time monitoring discounts.
Usage-based and on-demand insurance options emerge for short-term needs. Parametric solutions gain popularity for faster payouts bypassing traditional adjusters.
Conclusion
Home insurance delivers peace of mind when thoroughly understood and properly structured. It protects not just physical assets but financial futures against life's uncertainties. Regular policy reviews, accurate valuations, and open communication with insurers build robust protection.
Invest time in education and professional guidance. The right coverage transforms potential disasters into manageable events, allowing focus on what matters most—enjoying your home and family. Whether insuring a modest starter house or expansive estate, knowledge remains your strongest asset in navigating the complex insurance landscape.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
The GPS Watches market is projected to experience significant growth, with its size expected to reach approximately USD 5.02 billion by 2035. This represents a remarkable increase from USD 2.43 billion in 2024, reflecting a compound annual growth rate (CAGR) of 6.83%. As consumers prioritize health and fitness, the demand for advanced wearables is intensifying, highlighting the GPS watch sector...
Eyelid surgery has become one of the most sought-after cosmetic procedures for individuals looking to restore a youthful and refreshed appearance. Eyelid Surgery in Riyadh is especially popular due to the growing awareness of facial aesthetics and advanced cosmetic techniques available in the region. This procedure focuses on improving the appearance of droopy...
The cable tray market is witnessing steady growth due to the increasing demand for organized and efficient cable management systems across construction, manufacturing, and telecommunications industries. Cable trays play a vital role in supporting and protecting electrical wiring systems in commercial, industrial, and infrastructure projects. As urbanization accelerates...

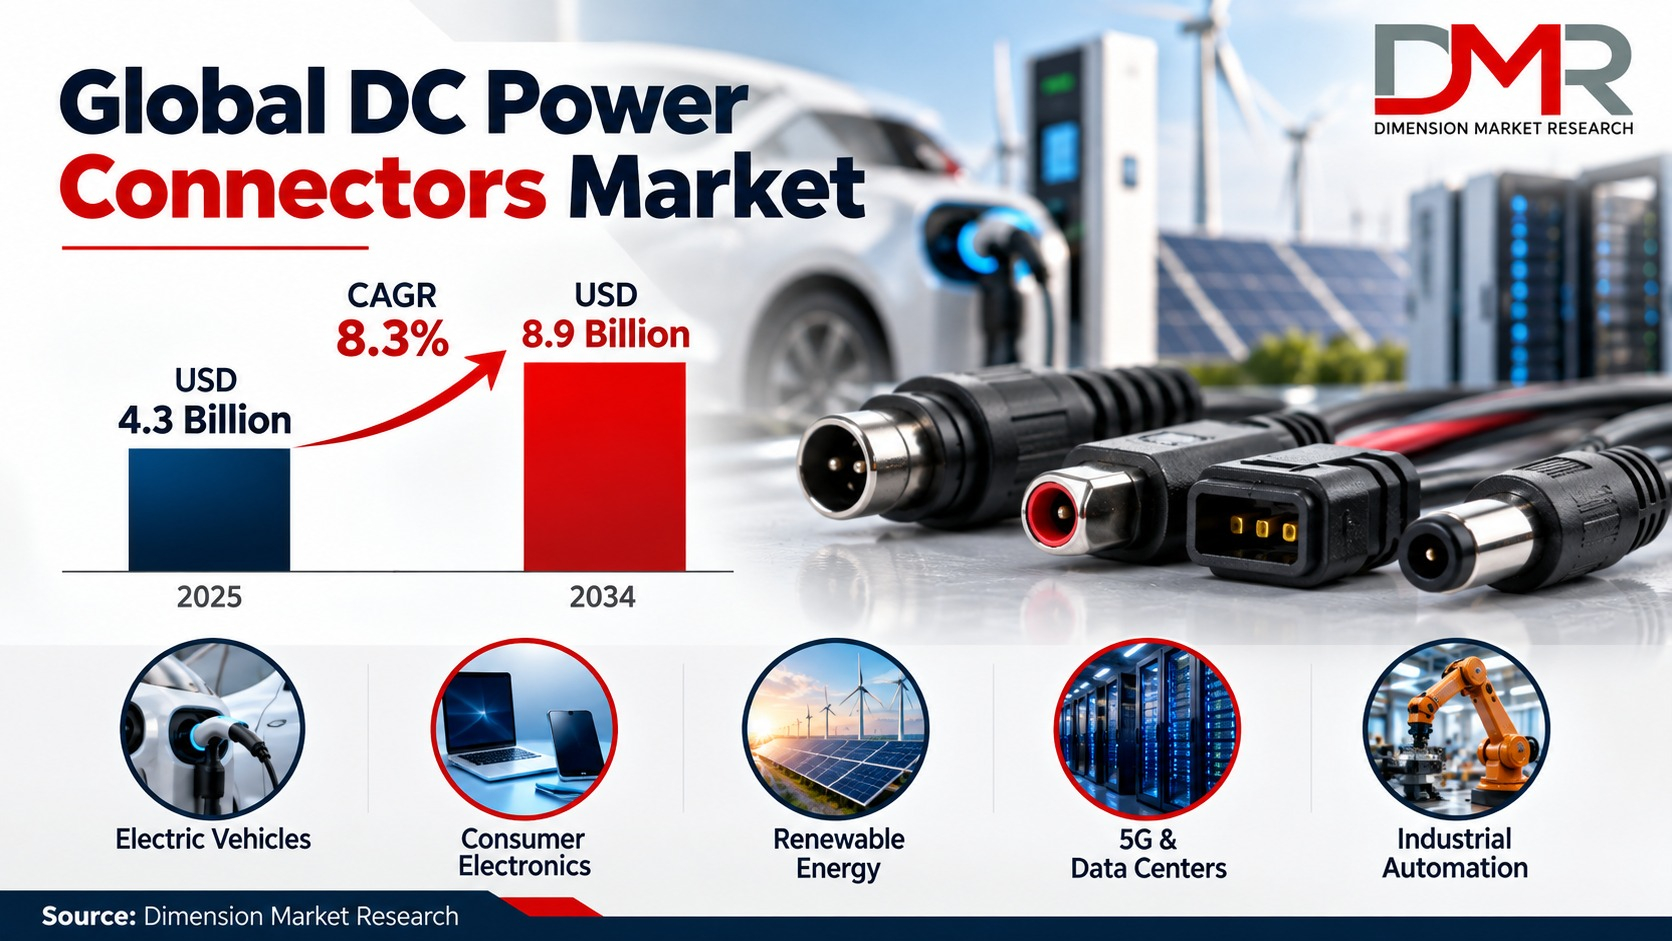
DC Power Connectors Market to Reach USD 8.9 Billion by 2034 The DC Power Connectors Market is projected to reach USD 4.3 billion in 2025 and is expected to expand at a CAGR of 8.3% from 2025 to 2034, reaching approximately USD 8.9 billion by 2034. According to Dimension Market Research, market expansion is being supported by increasing electronic device production, electric vehicle adoption,...
The increasing prevalence of chronic diseases, rising number of surgical procedures, and expanding hospital infrastructure are driving steady growth in the Intravenous Therapy Solutions Market. Intravenous (IV) therapy solutions are essential for delivering fluids, electrolytes, nutrients, blood products, and medications directly into the bloodstream, making them a cornerstone of...
