USA Pulp and Paper Market Size to Reach USD 14.79 Billion by 2035 at 3.01% CAGR
According to Market Research Future®, the USA Pulp and Paper Market Forecast estimates that the industry was valued at USD 10.67 billion in 2024 and is projected to increase to USD 11.02 billion in 2025 before reaching approximately USD 14.79 billion by 2035, expanding at a CAGR of 3.01% during the forecast period. The market continues to benefit from rising demand for sustainable packaging solutions, the rapid expansion of e-commerce, technological advancements in pulp and paper manufacturing, and growing utilization of recycled fiber. Leading companies including International Paper, WestRock, Georgia-Pacific, Domtar, Nippon Paper Industries USA, and Sappi Lanaken Mills are investing in production modernization, digital manufacturing, and sustainable resource management to strengthen their long-term competitive positions.
Market Overview
The United States pulp and paper industry continues to play a critical role within the country's manufacturing landscape by supplying essential materials for packaging, hygiene products, publishing, food service, healthcare, education, logistics, and numerous industrial applications. Although the market has experienced structural changes due to digital communication, it has successfully adapted by expanding into high-growth packaging and specialty paper segments that align with evolving consumer and commercial requirements.
Packaging has emerged as the industry's principal growth engine. The widespread adoption of online shopping, home delivery services, and omnichannel retailing has significantly increased demand for corrugated containers, paperboard, wrapping materials, and protective packaging. These products have become indispensable throughout modern supply chains, reinforcing the importance of domestic pulp and paper manufacturing.
Sustainability considerations have further accelerated industry transformation. Businesses across multiple sectors are actively replacing plastic packaging with renewable, recyclable paper alternatives in response to regulatory developments, corporate environmental commitments, and changing consumer preferences. As a result, manufacturers continue investing in recycled fiber utilization, responsible forestry practices, and advanced production technologies that improve resource efficiency while reducing environmental impacts.
The industry's resilience is also supported by continuous innovation. Automation, digital monitoring systems, advanced process controls, and artificial intelligence are improving production efficiency while enabling manufacturers to deliver higher-quality products with greater operational consistency.
Market Size
The USA pulp and paper market is projected to reach approximately USD 11.02 billion during 2025 before expanding to nearly USD 14.79 billion by 2035.
Steady demand from packaging manufacturers, sanitation product producers, industrial customers, and commercial applications provides a diversified revenue base that supports long-term industry stability.
Continued investments in manufacturing modernization and recycling infrastructure are expected to reinforce sustainable market expansion throughout the forecast period.
2025 Analysis
Market conditions during 2025 highlight the continued evolution of the United States pulp and paper sector toward higher-value and environmentally responsible product categories.
Wrapping and packaging remain the industry's largest revenue-generating category. Expanding e-commerce operations require significant quantities of corrugated boxes, shipping containers, paperboard packaging, protective inserts, and wrapping materials capable of supporting increasingly sophisticated logistics networks.
Sanitary paper products continue demonstrating stable demand due to consistent consumption across residential households, healthcare institutions, hospitality businesses, educational facilities, and commercial organizations. Tissue products remain among the industry's most resilient segments because of their essential nature.
Printing and writing papers continue serving educational institutions, publishing companies, financial organizations, and corporate offices. Although digital transformation has moderated long-term demand, specialized printing applications continue supporting production across selected market segments.
Newsprint remains relevant for certain publishing applications despite ongoing shifts in media consumption, while specialty papers continue expanding into industrial, healthcare, food service, and technical applications.
Manufacturers continue emphasizing production efficiency through investments in digital manufacturing systems, energy-efficient equipment, and automated quality control technologies that improve competitiveness while reducing operational costs.
2035 Forecast
The United States pulp and paper market is expected to approach USD 14.79 billion by 2035 as sustainable packaging, recycling initiatives, and manufacturing modernization continue reshaping industry demand.
Packaging applications are anticipated to remain the largest contributor to future growth. Continued expansion of e-commerce, food delivery services, and retail distribution networks will sustain demand for corrugated products and paper-based protective packaging.
Circular economy initiatives are expected to strengthen recycled fiber utilization throughout the industry. Growing investments in fiber recovery infrastructure, advanced sorting technologies, and efficient recycling systems will improve raw material availability while reducing environmental impacts.
Industrial automation and digital manufacturing technologies are likely to enhance operational efficiency, allowing manufacturers to optimize production while improving product quality and resource utilization.
Healthcare, food processing, consumer goods, and industrial manufacturing are also expected to remain significant end-use markets supporting long-term paper consumption.
Future Outlook
The long-term outlook for the United States pulp and paper industry remains favorable because market growth is supported by structural demand across multiple sectors rather than dependence on a single application.
Sustainability objectives, expanding logistics infrastructure, population growth, changing consumer preferences, and technological innovation collectively create a strong foundation for continued industry development.
Future competitiveness will increasingly depend upon manufacturers' ability to integrate operational excellence with environmentally responsible production, advanced recycling capabilities, and customer-focused product innovation.
Companies investing in digital transformation and sustainable manufacturing are expected to maintain stronger competitive positions throughout the forecast period.
Technology & Innovation
Technology continues transforming every stage of pulp and paper production.
Automation systems improve manufacturing precision, increase throughput, and reduce production variability while minimizing operating costs.
Artificial intelligence supports predictive maintenance, process optimization, and quality assurance, enabling manufacturers to improve plant reliability while reducing unplanned downtime.
Advanced fiber recovery technologies continue increasing recycled pulp utilization without compromising product performance. These innovations strengthen circular economy initiatives while reducing dependence on virgin fiber resources.
Energy-efficient production equipment, water conservation systems, and emissions reduction technologies are also improving environmental performance throughout manufacturing operations.
Digital monitoring platforms provide real-time operational visibility that enables continuous improvement across production facilities.
Growth Opportunities
Several structural trends continue creating significant opportunities for industry participants.
The continued expansion of e-commerce remains among the strongest long-term demand drivers for paper-based packaging solutions.
Corporate sustainability commitments continue accelerating adoption of recyclable paper packaging across food service, retail, healthcare, consumer goods, and industrial sectors.
Technological innovations in manufacturing provide opportunities to improve productivity, reduce operating expenses, and develop premium specialty paper products.
Growing investments in recycling infrastructure are expected to strengthen domestic fiber supply while improving long-term resource efficiency.
Specialty paper applications supporting healthcare, industrial manufacturing, and food packaging also represent attractive growth opportunities for manufacturers seeking product diversification.
Competitive Landscape
Competition within the United States pulp and paper industry is increasingly defined by manufacturing efficiency, sustainable sourcing practices, recycling capabilities, technological innovation, and customer service excellence.
Leading companies including International Paper, WestRock, Georgia-Pacific, Domtar, Nippon Paper Industries USA, and Sappi Lanaken Mills continue investing in advanced manufacturing technologies, production capacity expansion, digital process optimization, and environmentally responsible operations.
Strategic acquisitions, product portfolio diversification, and investments in recycled fiber processing continue strengthening competitive positioning while supporting long-term business growth.
Companies capable of balancing operational efficiency with sustainability leadership are expected to achieve stronger market performance as customer expectations continue evolving.
Recent Industry Developments
The industry continues modernizing through widespread adoption of automation, advanced analytics, and intelligent manufacturing systems that improve operational productivity and production quality.
Manufacturers are expanding investments in recycled fiber processing facilities to support circular economy objectives while reducing reliance on virgin raw materials.
Energy-efficient equipment upgrades and environmentally responsible production technologies continue improving manufacturing sustainability across production facilities.
Digital supply chain management systems are enhancing inventory visibility, procurement efficiency, and customer responsiveness throughout the value chain.
Research and development efforts remain focused on improving paper strength, printability, recyclability, barrier performance, and production efficiency to meet changing market requirements.
Professional Conclusion
The United States pulp and paper market is positioned for steady and sustainable growth through 2035, supported by expanding packaging demand, increasing utilization of recycled fiber, continuous manufacturing innovation, and evolving sustainability priorities. Although traditional paper consumption patterns continue changing, the industry's successful transition toward packaging, specialty products, and circular manufacturing has established a resilient foundation for long-term development.
Manufacturers that combine advanced production technologies, responsible resource management, operational efficiency, and innovative product development will be well positioned to capitalize on emerging opportunities across packaging, logistics, healthcare, food processing, and industrial applications. As sustainability continues shaping purchasing decisions throughout the economy, the United States pulp and paper industry is expected to remain an essential contributor to modern manufacturing and environmentally responsible supply chains.
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
Managed SOC Services in India: How IT Teams Can Strengthen Security Operations Modern IT environments are no longer limited to traditional office networks and on-premises infrastructure. Applications, cloud workloads, endpoints, identities, business systems, and remote access have created a broader security environment that needs continuous visibility. For many organizations, managed soc...
Fashion is constantly evolving, but one trend has remained consistent in recent years: the growing demand for accessories that combine style with practicality. Modern consumers no longer view backpacks as simple storage solutions. Instead, they expect them to enhance their outfits, reflect their personalities, and support their everyday lifestyles. Among the brands leading this transformation,...
This article provides a detailed Loan Management Software Market analysis, breaking down the market by deployment type, application, end user, and features. It offers insights into the dominant Cloud-Based, Mortgage Loans, Banks, and Loan Origination segments, and the fastest-growing On-Premises, Auto Loans, Online Lenders, and Collections Management segments. A thorough Loan...

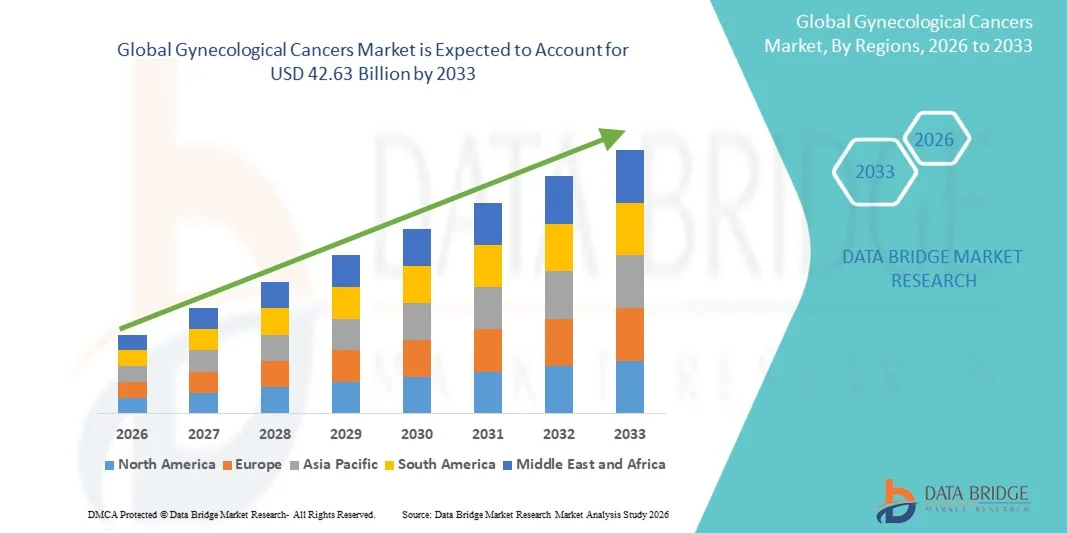
"According to the latest report published by Data Bridge Market Research, the Gynecological Cancers Market The global gynecological cancers market size was valued at USD 18.50 billion in 2025 and is expected to reach USD 42.63 billion by 2033, at a CAGR of 11.00% during the forecast period The wide ranging Gynecological Cancers Market report provides an overview of the...
The Mobile Phone Loudspeaker Market Solutions are driving innovation across the smartphone industry, with companies increasingly focusing on developing advanced loudspeaker solutions that address the evolving demands of audio quality, smart integration, and sustainability. Advanced solutions such as Samsung's Q and S series of wireless soundbars with Dolby Atmos support, Sony's...