Wireless Device Ecosystems Expand with 5G, Wi-Fi, IoT, and Edge Computing
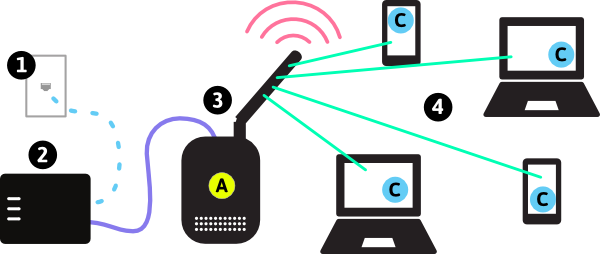
The Wireless Device industry within the Wireless Device Market is defined by products that connect without fixed cabling, spanning smartphones, tablets, laptops, wearables, hotspots, routers, industrial sensors, and embedded modules. What used to be a consumer electronics story is now an enterprise and industrial transformation story, because connectivity is becoming the default feature of nearly every device category. The market’s center of gravity is shifting from standalone hardware specs toward end-to-end experiences: reliable connectivity, battery efficiency, seamless handoffs between networks, and secure device management. This evolution is powered by multiple radio stacks—5G, LTE, Wi‑Fi 6/6E/7, Bluetooth, NFC, UWB, Zigbee/Thread, and LPWAN options—each chosen based on range, throughput, latency, and power budgets. As device fleets grow, organizations increasingly purchase wireless devices as part of broader ecosystems that include provisioning, identity, and lifecycle support. Interoperability and certification have become critical because a single environment may mix consumer BYOD endpoints with enterprise-grade managed devices and specialized industrial gear. Ultimately, the industry is converging around the idea that wireless devices are not endpoints; they are continuously updated, policy-governed nodes in a managed connectivity fabric.
Hardware innovation remains important, but it is more tightly coupled to radio and power design. Chipsets increasingly integrate multi-band radios, AI acceleration, and secure elements for authentication and encryption. Antenna design is also becoming a differentiator as device form factors shrink while supporting more bands and higher throughput. Battery technology and power-management firmware matter because always-on connectivity can drain small devices quickly, especially wearables and trackers. Across categories, manufacturers are optimizing for thermals and efficiency, enabling sustained high performance without overheating. The rise of eSIM/iSIM is changing device logistics by enabling remote carrier provisioning and easier global deployment. Meanwhile, ruggedized designs are expanding in logistics, field services, and manufacturing where devices face drops, moisture, chemicals, and vibration. In consumer segments, premium differentiation increasingly comes from camera systems, displays, and AI features, but wireless performance—call stability, Wi‑Fi roaming, and Bluetooth reliability—still strongly influences user satisfaction. These dynamics push vendors to co-design radios, software, and enclosures as a single system rather than independent components.
Software and services increasingly determine real-world performance in the Wireless Device Market. Operating systems manage radio scheduling, background processes, and security policies that affect both battery and connectivity quality. Device makers and enterprise IT teams now rely on OTA updates to patch vulnerabilities, add modem improvements, and tune performance for new networks. Mobile device management (MDM) and unified endpoint management (UEM) platforms are becoming standard in enterprises to enforce encryption, app controls, VPN settings, and compliance reporting. As organizations deploy more wireless endpoints, observability becomes valuable: monitoring signal quality, roaming failures, packet loss, and app-level performance. AI features are also entering wireless device software, helping optimize network selection, predict battery drain, and detect anomalies like rogue access points. The device’s role is expanding beyond communication into identity and payment, with biometrics, secure enclaves, and NFC enabling authentication and transactions. This creates new security requirements, including hardware-root trust, supply-chain integrity, and secure boot. As a result, vendors that combine robust radios with long-term software support and strong security posture are increasingly preferred.
Market adoption is also shaped by regulatory, spectrum, and sustainability considerations. Device makers must navigate regional spectrum allocations, certification processes, and SAR requirements, which can affect time-to-market and BOM cost. Geopolitical constraints and supply-chain dependencies influence component availability, particularly for modems, RF front-end parts, and power ICs. Sustainability expectations are rising: buyers and regulators push for repairability, longer OS support windows, recyclable materials, and reduced charger waste. Circular-economy programs—trade-ins, refurbished device channels, and fleet lifecycle extensions—are expanding in both consumer and enterprise procurement. In parallel, edge computing trends change device value: endpoints increasingly capture data locally and run AI inference before transmitting summaries, reducing bandwidth costs and improving privacy. Over time, the Wireless Device Market will favor vendors that deliver not just high specs, but consistent connectivity, security assurance, long support lifecycles, and measurable total cost of ownership for large fleets.
Top Trending Reports:
Categories
- Artificial Intelligence (AI)
- Technology
- Business
- Education
- Science
- Lifestyle
- Healthcare
- Entertainment
- Politics
- Environment
- Travel
- Finance
- Automobile
- News
- Art
- Causes
- Crafts
- career
- Dance
- Drinks
- Film
- Fitness
- Food
- Games
- Gardening
- Health
- Home
- Literature
- Music
- Networking
- Other
- Party
- Religion
- Shopping
- Sports
- Theater
- Wellness
Read More
The quickest way to drain a bankroll is to chase the flashiest slot on the screen before you’ve checked the return figure. That’s why Trybet Casino earns a spot in the research stage for players who want high RTP slots and a clearer long-term read on value. A game can look generous, too, with loud bonus rounds and bright animation, and still keep more of your money over time than a...

As per Market Research Future analysis, the Airborne ISR Market is projected to grow from USD 11.70 billion in 2026 to USD 21.25 billion by 2035, registering a CAGR of 6.85% during the forecast period. Increasing security challenges and rising investments in defense modernization programs are supporting the long-term growth of the industry. Governments worldwide are focusing on strengthening...

According to the latest report published by Data Bridge Market Research, the Rig and Oil Field Market The global rig and oil field market size was valued at USD 75.18 billion in 2024 and is expected to reach USD 124.43 billion by 2032, at a CAGR of 6.50% during the forecast period. An influential Rig and Oil Field Market advertising report puts light on the types of customers,...
Aircraft fuel cells are advanced energy conversion technologies that generate electrical power by combining hydrogen and oxygen through an electrochemical reaction. Unlike conventional aircraft engines that burn fossil fuels, fuel cells produce electricity with minimal emissions and improved energy efficiency. These systems are increasingly being explored for use in aircraft propulsion,...
The US Clinical Data Analytics Market is expanding as healthcare organizations increasingly use advanced analytics to improve patient outcomes, streamline operations, and support evidence-based decision-making. Market Research Future estimates that the market was valued at USD 1.85 billion in 2024 and is projected to reach USD 5.04 billion by 2035, registering a CAGR of 9.54% during...